Trident nuclear submarine replacement plans ‘unachievable’ – spending watchdog
RT | July 25, 2017
Multi-billion pound projects to upgrade and renew Britain’s nuclear arsenal have been branded “unachievable” by the Infrastructure and Projects Authority (IPA) in its report to the Treasury and Cabinet Office.
The watchdog’s report, which was picked up by the Ferret investigative website, found that major projects relating to the nuclear deterrent are poorly managed, over budget, and subject to technical difficulties.
Those projects are the £1.7 billion (US$2.2bn) nuclear reactor manufacturing program and the program to build four nuclear-armed and seven nuclear-powered submarines at a cost of £31 billion and £9 billion respectively.
The reactor manufacturing project, based at Rolls Royce in Derby, picked up the worst possible IPA rating after being marked as “red,” with the author’s warning that “successful delivery of the project appears to be unachievable.”
“There are major issues with project definition, schedule, budget, quality and/or benefits delivery, which at this stage do not appear to be manageable or resolvable.
“The project may need re-scoping and/or its overall viability reassessed,” the investigators added, warning that reactor building was £250,000 million ($325mn) over budget.
The submarine building project, which has so far delivered three nuclear-powered Astute–class warships, has been rated “amber/red” for the third successive year.
The IPA report said: “Successful delivery of the project is in doubt, with major risks or issues apparent in a number of key areas.
“Urgent action is needed to address these problems and/or assess whether resolution is feasible.”
The study found that “overall affordability” was the main impediment to the submarine building program.
As the submarines are bound for the UK’s nuclear base near Faslane, Scotland, the findings quickly attracted comment from the Scottish National Party (SNP) and anti-nuclear campaigners north of the border.
“A billion here – a billion there – to add to the bill for these weapons of mass destruction,” SNP defense spokesperson Stewart McDonald MP told the Ferret.
“The Westminster obsession with Trident is already squeezing conventional defense expenditure as everything else is sacrificed for these redundant, eye-wateringly expensive weapons. The Tories need to get a grip on costs if they insist on Trident renewal.”
Arthur West, the chairman of the Scottish Campaign for Nuclear Disarmament, told the website: “The Trident program in particular continues to be a shambles from a cost point of view.”
The Ministry of Defense defended the poor ratings, saying they “reflect the complexity and scale of delivering the most advanced submarines ever commissioned by the Royal Navy, the ultimate guarantee of our national security.”
The Fine Print: IMF Backs Down on Ukraine Land Reform Ultimatum, But at a Price
Sputnik – 23.07.2017
The International Monetary Fund has slightly relaxed its conditions for the provision of a new loan tranche to Ukraine, removing the demand that Kiev first revise the country’s laws on the privatization of agricultural land. Ukraine watchers Vladimir Zharikhin and Alexander Dudchak say that the IMF’s move is just a ploy designed to entrap Ukraine.
Last week, the IMF confirmed that it would not insist on the immediate implementation of land reform as a precondition for the provision of its next loan tranche to Ukraine in the fall.
Speaking at a press briefing on Thursday, IMF spokesman William Murray confirmed that land reform would not be on the agenda for the program revision meeting next month. “Land reform remains an important condition under the program. However, given the need to design the reform well and reach consensus on key steps ahead, there was a need to reset its timing to later in the year,” he said.
The IMF had earlier insisted that Kiev make changes to its land laws to allow for its privatization. Ukrainian lawmakers have stubbornly and repeatedly rejected these demands.
Other IMF loan conditions remain unchanged, and include pension reform, measures to accelerate privatization, and increased efforts against corruption, including the creation of an independent anti-corruption court. IMF conditions also include the requirement that Kiev continues with fiscal reform and restructuring of the energy sector, programs which have led to severe cuts in public spending, and skyrocketing utilities prices.
Ukraine has received four loan tranches worth $8.5 billion from the IMF since March 2015, when the program – worth $17.5 billion, was approved. Every successive tranche has been accompanied by long delays due to Kiev’s reticence to comply with the IMF’s requirements. The latest tranche, originally scheduled to be delivered in May, has now been postponed until September, pending Kiev’s compliance with the conditions.
In recent weeks and months, some Ukrainian authorities have tried to downplay the significance of the IMF loan program, signaling that it was needed mainly for the purpose of strengthening investor confidence in the country.
Last week, Prime Minister Volodymyr Groysman tried a different approach, complaining that Kiev does not have enough money to carry out the promised reforms, since most of the budget is spent on servicing foreign debt, defense and the pension fund. According to Groysman, Kiev now spends approximately 100 billion hryvnia – or 4% of its GDP, on debt servicing, with another 5% spent on security and defense.
Kiev is also expecting assistance from the EU in the form of a 600 million euro loan program. This program has its own conditionalities, including a cancellation of the moratorium on the sale of forestry products, and the lifting of import duties on certain goods. Kiev has until October to meet these conditions.
Experts say that without loans from the IMF, Brussels and the US, Kiev will have a more difficult time servicing its gross foreign debt, which currently stands at about $113 billion – or 66.8% of the country’s GDP. Public debt amounts to about $72 billion, 70% of that consisting of currency loans.
Speaking to the Svobodnaya Pressa online newspaper, Vladimir Zharikhin, deputy director of the Institute of CIS studies, said he was certain that the IMF would end up giving Ukraine its next loan tranche, since the money is needed to help shore up the current regime in Kiev. At the same time, he warned that the IMF will take every opportunity to squeeze Kiev along the path of austerity reforms.
“The IMF has a pulse on the situation in Ukraine,” Zharikhin said. “They have come to understand that pension reforms can be carried out, because pensioners feel intimidated, and do not pose a serious threat to the regime. As for corruption, this [conditionality] is always restricted to broad terms. A Special Committee on Corruption is functioning, but for some reason does not prosecute anyone. Basically this is just idle talk, while corruption increases. And in fact the IMF does not actively object to this.”
However, in the case of land reform, this is a sensitive issue for the authorities, according to the analyst, because it “affects the interests of a certain section of Ukraine’s political elite… The radical nationalist section of the elite and society opposes abolishing the moratorium on the sale of land, since they fear that land will be bought up by foreigners, including…Russian oligarchs. Therefore, the IMF decided to postpone land reform.”
In any case, the observer stressed that it was impossible to delay allocating the next loan tranche for long. “The IMF understands that doing so could lead to the complete collapse of the Ukrainian economy and the fall of the current regime.” This, Zharikhin emphasized, would not be in the interests of either the Fund itself, or its US sponsors.
Put crudely, the observer said that IMF tranches are allocated mainly “to keep Kiev’s pants from falling down,” and little else. “Factually, this is what they’ve been doing in the last few years now.”
Nonetheless, Zharikhin stressed that in the end, the IMF will never back down from any of its austerity demands for good, instead working more closely with Ukraine’s political and economic elite to return to the trouble spot when the time is right.
For his part, Ukrainian political scientist and economist Alexander Dudchak told Svobodnaya Pressa that whatever else happens, Kiev’s “addiction” to IMF loans, and specifically their requirement for major socioeconomic reforms, will have disastrous long-term consequences for Ukraine, even if the country’s Maidan-installed authorities were to be removed from power.
In the meantime, Dudchak noted that while all of the IMF’s conditions will continue to have a painful impact on ordinary Ukrainians’ lives, the land issue is a particularly sensitive one.
“If the moratorium [on the sale of land] is lifted, nothing will remain of Ukrainian lands. They will not belong to the state or the people. Ukrainian agro-holdings, which today are considered among the country’s strongest enterprises, will not be able to compete against transnational capital. Ukraine will be deprived of its land and its population gradually returned to the status of serfs.”
As far as the current government is concerned, they are delaying land reform only because they would like to write the new laws on privatization with their own interests in mind, Dudchak said. But whatever they end up doing, “it will be hard for them to prevent foreigners from gaining control over farmland and growing whatever they want there, up to and including genetically-modified foods.”
As for the latest IMF tranche, the economist stressed that it will be spent in its entirety on servicing Ukraine’s massive debts. Otherwise, “for Ukraine as a state the benefit from this loan is zero.”
QE, the largest transfer of wealth in history
By Dan Glazebrook | RT | July 22, 2017
It appears that the massive, almost decade-long transfer of wealth to the rich known as ‘quantitative easing’ is coming to an end.
Of the world’s four major central banks – the US Federal Reserve, the Bank of England, the European Central Bank and the Bank of Japan – two have already ended their policy of buying up financial assets (the Fed and the BoE), and the ECB plans to stop doing so in December. Indeed, the Fed is expected to start selling off the $3.5 trillion of assets it purchased during three rounds of QE within the next two months.
Given that – judged by its official aims – QE has been a total failure, this makes perfect sense. By ‘injecting’ money into the economy, QE was supposed to get banks lending again, boosting investment and driving up economic growth. But overall bank lending in fact fell following the introduction of QE in the UK, whilst lending to small and medium sized enterprises (SMEs) – responsible for 60 percent of employment – plummeted.
As Laith Khalaf, a senior analyst at Hargreaves Lansdown, has noted: “Central banks have flooded the global economy with cheap money since the financial crisis, yet global growth is still in the doldrums, particularly in Europe and Japan, which have both seen colossal stimulus packages thrown at the problem.”
Even Forbes admits that QE has “largely failed in reviving economic growth”.
This is, or should be, unsurprising. QE was always bound to fail in terms of its stated aims, because the reason banks were not funneling money into productive investment was not because they were short of cash – on the contrary, by 2013, well before the final rounds of QE, UK corporations were sitting on almost £1/2trillion of cash reserves – but rather because the global economy was (and is) in a deep overproduction crisis. Put simply, markets were (and are) glutted and there is no point investing in glutted markets.
This meant that the new money created by QE and ‘injected’ into financial institutions – such as pension funds and insurance companies – was not invested into productive industry, but rather went into stock markets and real estate, driving up prices of shares and houses, but generating nothing in terms of real wealth or employment.
Holders of assets such as stocks and houses, therefore, have done very well out of QE, which has increased the wealth of the richest 5 percent of the UK population by an average of £128,000 per head.
How can this be? Where does this additional wealth come from? After all, while money – contrary to Tory sloganeering – can indeed be created ‘out of thin air’, which is precisely what QE has done, real wealth cannot. And QE has not produced any real wealth. Yet the richest 5 percent now have an extra £128,000 to spend on yachts, mansions, diamonds, caviar and so on. So where has it come from?
The answer is simple. The wealth which QE has passed to asset-holders has come, first of all, directly out of workers’ wages. QE, by effectively devaluing the currency, has reduced the buying power of money, leading to an effective decrease in real wages, which, in the UK, still remain 6 percent below their pre-QE levels. The money taken out of workers’ wages therefore forms part of that £128,000 dividend. But it has also come from new entrants to the markets inflated by QE – primarily, first time buyers and those just reaching pension age.
Those buying a house (which QE has made more expensive), for example, will likely have to work thousands of additional hours over the course of their mortgage in order to pay this increased cost. It is those extra hours that are creating the wealth which subsidizes the spending spree for the richest 5 percent. Of course, these increased house prices are paid by anyone purchasing a house, not only first time buyers – but the additional cost for existing homeowners is compensated for by the rise in price of their existing house (or by their shares for those wealthy enough to hold them).
QE also means that newly retiring pensioners are forced to subsidize the 5 percent. New retirees use their pension pot to purchase an ‘annuity’ – a bundle of stocks and shares generating dividends which serve as an income. However, as QE has inflated share prices, the number of shares they can buy with this pot is reduced. And, as share price increases do not increase dividends, this means reduced pension payments.
In truth, the story that QE was about encouraging investment and boosting employment and growth was always a fantastical yarn designed to disguise what was really going on – a massive transfer of wealth to the rich.
As economist Dhaval Joshi put it in 2011: “The shocking thing is, two years into an ostensible recovery, [UK] workers are actually earning less than at the depth of the recession. Real wages and salaries have fallen by £4bn. Profits are up by £11bn. The spoils of the recovery have been shared in the most unequal of ways.”
In March this year, the Financial Times noted that while Britain’s GDP had recovered to pre-crisis levels by 2014, real wages were still 10 percent lower than they had been in 2008. “The contraction of UK real wages was reversed in 2015,” they added, “but it is not going to last”. They were right. The same month the article was published, real wages began to fall again, and have been doing so ever since.
It is the same story in Japan, where, notes Forbes, “household income actually contracted since the implementation of QE”.
QE has had a similar effect on the global South: enriching the holders of assets at the expense of the ‘asset-poor’. Just as the influx of new money created bubbles in the housing and stock markets, it also created commodity price bubbles as speculators rushed to buy up stocks of, for example, oil and food. For some oil producing countries this has had a positive effect, providing them a windfall of cash to spend on social programs, as was initially the case in, for example, Venezuela, Libya and Iran. In all three cases, the empire has had to resort to various levels of militarism to counter these unintended consequences. But oil price hikes are, of course, detrimental to non-oil-producing countries – and food price hikes are always devastating.
In 2011, the UK’s Daily Telegraph highlighted “the correlation between the prices of food and the Fed’s purchase of US Treasuries (i.e. its quantitative easing programs)… We see how the food price index broadly stabilized through late 2009 and early 2010, then rose again from mid-2010 as quantitative easing was re-started … with prices rising about 40 percent over an eight month period.”
These price hikes pushed 44 million people into poverty in 2010 alone – leading, argued the Telegraph, to the unrest behind the so-called Arab Spring. Former World Bank president Robert Zoellick commented at the time that: “Food price inflation is the biggest threat today to the world’s poor… one weather event and you start to push people over the edge.”
Such are the costs of quantitative easing.
The BRICS economies were also critical of QE for another reason: they saw it as an underhand method of competitive currency devaluation. By reducing the value of their own currencies, the ‘imperial triad’ of the US, Europe and Japan were effectively causing everyone else’s currencies to appreciate, thereby damaging their exports. Forbes wrote in 2015, “The effects are already being felt in the most dynamic exporter in the world, the East Asian economies. Their exports in US dollar terms moved dramatically from 10 percent year-on-year growth to a contraction of 12 percent in the first half of this year; and the results are the same whether China is excluded or not.”
The main benefit of QE to the developing world is supposed to have been the huge inflows of capital it triggered. It has been estimated that around 40 percent of the money generated by the Fed’s first QE credit expansion (‘QE1’) went abroad – mostly to the so-called ‘emerging markets’ of the global South – and around one third from QE2. However, this is not necessarily the great boon it seems. Much of the money went, as we have seen, into buying up commodity stocks (making basic items such as food unaffordable for the poor) rather than investing in new production, and much also went into buying up stocks of currency, again causing an export-damaging appreciation. Worse than this, an influx of so-called ‘hot money’ (footloose speculative capital, as opposed to long term investment capital) makes currencies particularly volatile and vulnerable to, for example, rises in interest rates abroad.
Should interest rates rise again in the US and Europe, for example, this is likely to trigger a mass exodus of capital from the emerging markets, potentially prefiguring a currency collapse. Indeed, it was an influx of ‘hot money’ into Asian currency markets very similar to that seen during QE which preceded the Asian currency crisis of 1997.
It is precisely this vulnerability which is likely to be tested – if not outright exploited – by the coming end of QE and accompanying rise of interest rates.
Dan Glazebrook is a freelance political writer who has written for RT, Counterpunch, Z magazine, the Morning Star, the Guardian, the New Statesman, the Independent and Middle East Eye, amongst others. His first book “Divide and Ruin: The West’s Imperial Strategy in an Age of Crisis” was published by Liberation Media in October 2013. It featured a collection of articles written from 2009 onwards examining the links between economic collapse, the rise of the BRICS, war on Libya and Syria and ‘austerity’. He is currently researching a book on US-British use of sectarian death squads against independent states and movements from Northern Ireland and Central America in the 1970s and 80s to the Middle East and Africa today.
Class War on the Waterfront: Longshore Workers Under Attack
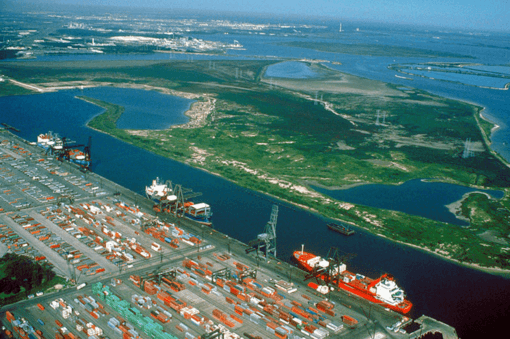
Photo by ROBERT HUFFSTUTTER | CC BY 2.0
By Jack Heyman | CounterPunch | July 21, 2017
The ink wasn’t even dry on the West Coast longshore contract when the head of the employers’ group, the Pacific Maritime Association, proposed an additional 3-year extension to the president of the International Longshore and Warehouse Union (ILWU), making it an eight-year contract. While the number of registered longshore jobs, 14,000, is the about same as in 1952, revenue tonnage has increased 14 times to a record-breaking 350 million revenue tons.
Under the current contract employers have already eliminated hundreds of longshore jobs through automation on marine terminals like the fully-automated Long Beach Container Terminal and semi-automated TraPac in the port of Los Angeles. “By the end of an extended contract in 2022, several thousand longshore jobs will be eliminated on an annual basis due to automation” warned Ed Ferris, president of ILWU Local 10 of San Francisco. With driverless trucks and crane operators in control towers running three cranes simultaneously, the chances of serious and deadly accidents are enormous.
Now maritime employers are pulling out all stops to push through this job-killing contract extension, using both Democratic and Republican politicians, high-powered PR firms and even some union officials.
A Chronicle op-ed appeared this week by Democrat Mickey Kantor, former Secretary of Commerce who was responsible for creating the World Trade Organization and the North American Free Trade Association which lost millions of jobs and Norman Mineta, another Democrat former Secretary of Commerce, from the public relations firm Hill and Knowlton. The first public relations firm was hired by Rockefeller to clean up his public image after nearly 100 people, men, women and children were killed in a 1914 Colorado miners strike known as the Ludlow Massacre and employers continue to use PR firms today.
The authors of this week’s SF Chronicle pro-company PR piece talk of preserving “labor peace” and refer to West Coast port shutdowns over the last 15 years. Yes, there is a class war on the waterfront, but it’s being waged by the employers. Those port closures were caused by employer lockouts in 2002, 2013 and 2014 during longshore contract negotiations. The 2002 lockout was ended after Democrat Diane Feinstein called on President Bush to invoke the anti-labor Taft-Hartley Act directed not against the maritime employers’ lockout but the longshore union. The only time the ILWU shutdown Pacific Coast ports in that period was May Day 2008 to protest the wars in Iraq and Afghanistan in the first-ever labor strike in the United States against a war.
The two Democrats cite distorted figures for wages and pensions that only reflect the highest skill level after a lifetime of work in one of the most dangerous industries. And then they threaten that “if the contract proposal is rejected” it could lead Republicans and Democrats alike to impose anti-strike legislation on the waterfront. The ILWU backed Bernie Sanders in the last election and then Hillary Clinton. Yet no matter who leads it, the Democratic Party represents the employer class, Wall Street on the waterfront. Clearly what’s needed now is a workers party to fight for a workers government that would expropriate the maritime industry, in ports and at sea, while establishing workers control.
The so-called “friends of labor” Democrats have been enlisted by PMA because earlier this year at the Longshore Caucus, a union meeting representing dockworkers on all West Coast ports, the San Francisco longshore delegates voted unanimously to oppose a contract extension. Last week they held a conference at their union hall on automation and the proposed contract extension. One proposal was to make automation benefit dockworkers by reducing the workweek to 30 hours while maintaining 40 hours pay, creating another work shift.
There are tens of millions of unemployed in this country. The labor movement should launch a new campaign for a shorter workweek at no loss in pay as part of a struggle for full employment to benefit all, not Trump and his Wall Street bankster cronies. In resisting the push for this contract extension to automate jobs out of existence, ILWU waterfront workers can stand up for all workers.
Jack Heyman is a retired Oakland longshoreman who edits the Maritime Worker Monitor and chairs the Transport Workers Solidarity Committee.
US corporations lobby against anti-Russia sanctions
RT | July 21, 2017
A wide range of American conglomerates, including oil, energy, banking, aerospace, auto and heavy manufacturing enterprises have jointly started a lobbying campaign against the new round of sanctions against Russia passed by the US Senate, CNN reports.
BP, ExxonMobil, General Electric, Boeing and Citigroup, MasterCard and Visa are reportedly among the companies raising concerns the punitive measures will ultimately harm their businesses, rather than the Kremlin.
Ford, Dow Chemical, Procter & Gamble, International Paper, Caterpillar, and Cummins have reportedly warned the measure could impact their businesses as well.
The new bill, aimed at punishing Russia for alleged meddling in the US presidential election, was approved last month. The measures target already sanctioned Russian banks and energy sector, limiting the financing period for them to 14 and 30 days respectively.
The legislation also introduces individual sanctions for investing more than $5 million a year or $1 million at a time in Russian pipeline projects or providing such enterprises with services, technology or information support.
Over a dozen of US corporations want changes to the bill and lobbyists and trade associations have been visiting Capitol Hill in recent days meeting members of Congress.
“It passed with such force and such a strong vote in the Senate, it seemed to be insurmountable initially. I don’t think they thought through the unintended consequences,” said a senior congressional aide who has worked on the billб as quoted by the media outlet.
The bill, which is still to be approved by both the House of Representatives and the Trump administration has drawn a wave of criticism among European corporations as well.
Earlier this week, the heads of European energy companies warned the sanctions Washington wants to impose on the Nord Stream-2 gas pipeline might have an adverse impact on Europe.
Last month, German Foreign Minister Sigmar Gabriel and Austrian Chancellor Christian Kern said the new measures introduced by the US were only about “selling American liquefied natural gas and ending the supply of Russian natural gas to the European market.”
US adding new sanctions against Iran over missile program
Press TV – July 18, 2017
The administration of US President Donald Trump says it is imposing new economic sanctions against Iran over the Islamic Republic’s ballistic missile program.
The US Departments of Treasury and State said Tuesday they are targeting 18 Iranian individuals, groups and networks.
The new sanctions freeze any assets the targets may have in the US and prevents Americans from doing business with them.
The restrictions ranged from a company that allegedly aided Iran’s drone program to a Turkey-based provider of naval equipment and a China-based network that provided electronics to Iran, according to the Associated Press.
Treasury Secretary Steven Mnuchin said the sanctions “send a strong signal that the United States cannot and will not tolerate Iran’s provocative and destabilizing behavior.”
The move comes one day after the Trump administration certified to Congress that Iran is in compliance with the 2015 nuclear agreement, which lifted nuclear-related sanctions imposed against Tehran.
The Trump administration notified the Congress of Iran’s compliance for the first time in April.
The White House is bound by US law to notify Congress of Iran’s compliance with the nuclear deal every 90 days. The Trump administration had notified the Congress of Iran’s compliance for the first time in April.
The certification that Iran is technically complying with the nuclear agreement clears the way for sanctions to remain lifted.
Washington claims Iran’s missile program is in breach of United Nations Security Council Resolution 2231, which endorsed Tehran’s nuclear deal with the P5+1 states in 2015.
However, Tehran insists its missile tests do not breach any UN resolutions because they are solely for defense purposes and not designed to carry nuclear warheads.
The Islamic Republic has said it will spare no effort to meet its national security needs, and does not allow any party to intervene in the imperative.
Big Military Spending Boost Threatens Our Economy and Security
By Ron Paul | July 17, 2017
On Friday the House overwhelmingly approved a massive increase in military spending, passing a $696 billion National Defense Authorization bill for 2018. President Trump’s request already included a huge fifty or so billion dollar spending increase, but the Republican-led House found even that to be far too small. They added another $30 billion to the bill for good measure. Even President Trump, in his official statement, expressed some concern over spending in the House-passed bill.
According to the already weak limitations on military spending increases in the 2011 “sequestration” law, the base military budget for 2018 would be $72 billion more than allowed.
Don’t worry, they’ll find a way to get around that!
The big explosion in military spending comes as the US is planning to dramatically increase its military actions overseas. The president is expected to send thousands more troops back to Afghanistan, the longest war in US history. After nearly 16 years, the Taliban controls more territory than at anytime since the initial US invasion and ISIS is seeping into the cracks created by constant US military action in the country.
The Pentagon and Defense Secretary James Mattis are already telling us that even when ISIS is finally defeated in Iraq, the US military doesn’t dare end its occupation of the country again. Look for a very expensive array of permanent US military bases throughout the country. So much for our 2003 invasion creating a stable democracy, as the neocons promised.
In Syria, the United States has currently established at least eight military bases even though it has no permission to do so from the Syrian government nor does it have a UN resolution authorizing the US military presence there. Pentagon officials have made it clear they will continue to occupy Syrian territory even after ISIS is defeated, to “stabilize” the region.
And let’s not forget that Washington is planning to send the US military back to Libya, another US intervention we were promised would be stabilizing but that turned out to be a disaster.
Also, the drone wars continue in Somalia and elsewhere, as does the US participation in Saudi Arabia’s horrific two year war on impoverished Yemen.
President Trump often makes encouraging statements suggesting that he shares some of our non-interventionist views. For example while Congress was shoveling billions into an already bloated military budget last week, President Trump said that he did not want to spend trillions more dollars in the Middle East where we get “nothing” for our efforts. He’d rather fix roads here in the US, he said. The only reason we are there, he said, was to “get rid of terrorists,” after which we can focus on our problems at home.
Unfortunately President Trump seems to be incapable of understanding that it is US intervention and occupation of foreign countries that creates instability and feeds terrorism. Continuing to do the same thing for more than 17 years – more US bombs to “stabilize” the Middle East – and expecting different results is hardly a sensible foreign policy. It is insanity. Until he realizes that our military empire is the source of rather than the solution to our problems, we will continue to wildly spend on our military empire until the dollar collapses and we are brought to our knees. Then what?
US looks to become major oil exporter – report
RT | July 13, 2017
The US may transform into one of the world’s top oil exporters in only a few short years due to its production increase of shale oil, an energy consulting group says.
The consultancy PIRA energy group has released a new forecast relating to the current boom of US shale oil production. The group has estimated that by 2020, US crude exports will rise to 2.25 million barrels a day. This means the production would grow to four times the amount of what was produced last year. The recent uptick of crude production in the US looks to weaken the strength of OPEC exporting countries, according to CNN Money.
This boom would put the US almost on the same level as giant oil exporters such as Kuwait and the United Arab Emirates. Jenna Delaney, an analyst at PIRA, said that “in the years ahead, these developments position the US to potentially be one of the largest exporters of crude oil in the world,” CNN reported.
Various American cities may play a big role in the success of the US export market. One city in Texas was named specifically. Delaney commented that “PIRA believes Corpus Christi is positioned to become an increasingly prominent area for US exports.”
She continued, “Corpus Christi’s proximity to the Eagle Ford formation and projected pipeline expansions connecting it to the Permian offer it access to cheap supplies, infrastructure projects, both private and public, will allow for greater export scale,” according to the Oil and Gas Journal.
There are rival countries keeping an eye on the situation in the US. OPEC, which encompasses 14 countries, was exporting an average of 25 million barrels a day in 2016. These countries stand to lose a lot due to the rise of American oil crude exports.
The US will look to rise in the ranks and start to diminish the influence of the organization in the next few years. Saudi Arabia, a top ranking member, was a top exporter last year. They sent 7.5 million barrels into other countries last year, according to CNN.
The uptick in US production of crude oil is very surprising considering the country had banned the exports way back in 1975 and only lifted the ban in 2015, according to the Economist.
An increase in the production of shale is the main reason for the surge, Delaney said. In 2014, “the industry was hit hard by a collapse in oil prices. Major producers of oil were forced to reduce investment and production declined overall,” CNN reported.
After the collapse, operators started to be more efficient in the industry. The production of US crude began to slowly grow to reach 9 million barrels a day in February 2017, the US Energy Information Administration reported, according to CNN.
As the US is supposed to ascend to the top of the ranks in crude exports, allegations have arisen that Russia is working with environmentalists in America in order to undermine the shale oil industry.
Representative Lamar Smith, (R-Texas), along with Randy Weber (R-Texas), have sent a letter, dated June 29, to US Treasury Secretary Steven Munchin, alleging that Russia is funding environmentalist groups who spoke out against health concerns related to shale drilling, in order to protect the independence of Russian gas imports. However, the letter states that there is “no paper trail” leading to any strategy set forth by Russia, The Daily Signal reported.
BDS gains support from US Mennonite churches
MEMO | July 12, 2017
The Mennonite Church of America has voted to sell its holdings in companies that profit from the Israeli occupation, according to the Washington Post.
The church, which has over 75,000 members voted by a majority of 98 per cent to support the Boycott Divestment Sanctions (BDS) campaign last week in Orlando.
The resolution voted upon, called on “individuals and congregations to avoid the purchase of products associated with acts of violence or policies of military occupation, including items produced in [Israeli] settlements.”
In a statement, the Mennonite Church explained its decision: “The Palestinian people have suffered injustices, violence, and humiliation, including … life under Israeli military occupation and in refugee camps throughout the Middle East.”
The church has also turned to their own $3 billion fund and asked investment managers to review all investment practices that may benefit the ongoing Israeli occupation.
Numerous churches in the US have also committed to a divestment campaign of Israeli goods, including the Presbyterian Church, the United Church of Christ, the Quakers, the Unitarian Universalists and the Evangelical Lutheran Church. Whilst the 12.8 million-member United Methodist church did not move to support BDS outright, they have barred investment in five Israeli banks citing human rights concerns.
Read also: BDS campaign supported by African churches
Featured Video
False Flags and the Dawn of Bioterrorism
or go to
Aletho News Archives – Video-Images
From the Archives
How 1960’s French Nuclear Tests Are Still Claiming Lives in Algeria
Sputnik – 15.02.2018
On February 13, 1960, France carried out its first nuclear test in Algeria’s southern Reggane region. According to official statistics, 17 nuclear tests were carried out in total over the next 6 years. The area remains affected, and local scientists say that radioactive contamination has caused genetic mutations and irreversibly changed the region.
There are no official statistics on the number of victims. The only figures can be found in the records kept by the French representative of the local church, which lists 42,000 victims of nuclear tests. Three years ago, the French Ministry of Defense issued a statement, putting the number at 27,000 people. The victims include French soldiers as well as local Algerians who lived in the surrounding areas. … continue
Blog Roll
 Aletho News
- Using nuclear weapons, the US-Israeli alliance still can’t beat Iran
- Sunset on the Quality of Western Propaganda: Arrival of the Dr Strangelove Moment
- Ukrainian general accused of protecting crime bosses
- US-‘Israel’ alliance faces growing rupture after midterms
- GOP’s Crushing Midterm Loss Could Reshape US Political Landscape – Analyst
- Midterm loss gives Congress power to rein in US war on Iran
- Midterms Were ‘Vote of No Confidence’ in GOP, But Iran Has No Illusions About Democrats – Marandi
- Israeli Soldiers Inadvertently Prove Their Own Genocidal Guilt
- Ukraine arrests woman who exposed Azov battalion’s ‘torture chamber’
- Did Israel lose the midterms?
- If Americans Knew
- An error has occurred; the feed is probably down. Try again later.
- No Tricks Zone
- New Study: The Net Fossil Fuel Contribution To Rising Atmospheric CO2 Has Been Zero For 500 Years
- Germany’s Green Energy Transition Becoming Increasingly Expensive…Another 6 Trillion Euros!
- Sudden Stratospheric Warming, Powerful El Niño Combination May Lead To Extreme Europe Cold, Energy Crisis!
- Two New Studies Find Thwaites Glacier Melt Cannot Be Driven By Human Activity Or A Warming Ocean
- E-Cars Reduce CO2 Emissions By Only 41% Compared To Internal Combustion Engine Vehicles
- Predictions Made By Renowned Climate Professor Over Past Decades Have Been Proven To Be Poor
- New Study Suggests Large Regions Of The Pacific Ocean Have Been Cooling For The Last 80 Years
- Germany’s Green Energy Debacle: High Energy Costs Force Kahla Porzellan to Close After 182 Years!
- New Study: 50 Years Of The Most Aggressive ‘Net Zero’ Policies Can Only Affect The Global Climate By 0.03°C
- US September “Heat” Was No Record…Many Records Set Decades Ago

