FT: “Seoul finds new way to finance Iran trade”
This past September, The Wall Street Journal Asia’s editorial board heralded the Japanese and South Korean enforcement of UN sanctions against Iran as “worth cheering” and a sign that South Korea was “growing up as a democracy.”
But the news today that South Korea has appointed two state-run banks to finance trade with Iran, might make the WSJ editorial board rethink their premature exuberance over the effectiveness of the sanctions regime.
Christian Oliver, Song Jung-a and Anna Fifield write in the Financial Times:
The US had pressured South Korea to cut out trade with Iran following the imposition of sanctions in September. Washington praised Seoul when South Korea announced its own measures.
Soon after the sanctions announcement, however, South Korea quietly reached a financing agreement with the Iranian central bank to buttress trade.
Seoul says that from this month Woori Bank and the Industrial Bank of Korea can finance legitimate trade with Iran in sectors unaffected by sanctions.
South Korea has a $10 billion annual trade relationship with Iran and is clearly eager to retain what commerce they can with the Islamic Republic.
Seoul’s effort to find ways of maintaining its commercial relationships with Iran is yet another example of the challenge of imposing a sanctions regime on Iran, which has a diverse and well established set of trading relationships in the increasingly globalized and interconnected economy.
The FT article says:
But in Washington officials said the South Korean move would increase transparency in dealings with Iran. “This is a measure to ensure that some of the shadier private banks in Iran are not involved [in business transactions],” said a state department spokesman.
The Iranian central bank will deposit proceeds from oil sales in South Korea at Woori and IBK. The funds will be used to ensure payments for South Korean exporters that had been retreating from Iran.
America’s Third World Economy
The Great Transformation
By PAUL CRAIG ROBERTS | October 8, 2010
For a number of years I reported on the monthly non-farm payroll jobs data. The data did not support the praises economists were singing to the “New Economy.” The “New Economy” consisted, allegedly, of financial services, innovation, and high-tech services.
This economy was taking the place of the old “dirty fingernail” economy of industry and manufacturing. Education would retrain the workforce, and we would move on to a higher level of prosperity.
Time after time I reported that there was no sign of the “New Economy” jobs, but that the old economy jobs were disappearing. The only net new jobs were in lowly paid domestic services such as waitresses and bartenders, retail clerks, health care and social assistance (mainly ambulatory health care services), and, before the bubble burst, construction.
The facts, issued monthly by the US Bureau of Labor Statistics, had no impact on the ”New Economy” propaganda. Economists continued to wax eloquently about how globalism was a boon for our future.
The millions of unemployed today are blamed on the popped real estate bubble and the sub-prime derivative financial crisis. However, the US economy has been losing jobs for a decade. As manufacturing, information technology, software engineering, research, development, and tradable professional services have been moved offshore, the American middle class has shriveled. The ladders of upward mobility that made American an “opportunity society” have been dismantled.
The wage and salary cost savings obtained by giving Americans’ jobs to Chinese and Indians have enriched corporate CEOs, shareholders, and Wall Street at the expense of the middle class and America’s consumer economy.
The loss of middle class jobs and incomes was covered up for years by the expansion of consumer debt to substitute for the lack of income growth. Americans refinanced their homes and spent the equity, and they maxed out their credit cards.
Consumer debt expansion has run its course, and there is no possibility of continuing to drive the economy with additions to consumer debt.
Economists and policymakers continue to ignore the fact that all employment in tradable goods and services can be moved offshore (or filled by foreigners brought in on H-1b and L-1 visas). The only replacement jobs are in nontradable domestic services, that is, those jobs that require “hands-on” activity, such as ambulatory health services, barbers, cleaning services, waitresses and bartenders–jobs that describe the labor force of a third world country. Even many of these jobs are now filed with foreigners brought in on R-1 type visas from Russia, Ukraine, Thailand, Romania, and elsewhere.
The loss of American jobs and the compression of consumer income by low wages has removed consumer demand as the driving force of the economy. This is the reason expansionary monetary and fiscal policies are having no effect.
The latest jobs report issued today shows that America’s transformation into a third world economy continues. The economy lost 95,000 jobs in September, mainly due to cuts in local education and federal employment. Part of the loss of 159,000 government jobs was offset by 64,000 new private sector jobs.
Where are the new jobs? They are in nontradable lowly paid domestic services: 32,000 were in health care and social services, and 33,900 were in food services and drinking places.
There you have it. That is America’s “New Economy.”
Paul Craig Roberts was an editor of the Wall Street Journal and an Assistant Secretary of the U.S. Treasury. His latest book, HOW THE ECONOMY WAS LOST, has been published by CounterPunch/AK Press. He can be reached at: PaulCraigRoberts@yahoo.com
Related article
- The Offshore Outsourcing of American Jobs: A Greater Threat Than Terrorism (blacklistednews.com)
Census Data: America Got Poorer in 2009
By Max Fraad-Wolff | t r u t h o u t | 28 September 2010
2009 was a year of accelerating economic pain and loss, according to US Census data released today. Although the National Bureau of Economic Research (NBER) tells us that the “Great Recession” officially ended in December of 2009, the labor force of the US shrank by more than 130,000 from 2008 to 2009. The median family income – a better measure than average income because it reflects the exact middle of income distribution – decreased by $2,254 or 3.5 percent. The median income for all workers in the US fell from $29,868 in 2008 to $28,365 in 2009 – a 5 percent decline.
A staggering 48 percent of households earned less than $50,000 per year in 2008, but in 2009, 49.8 percent of households earned less than $50,000. What’s more, income per person in the US declined from $27,589 in 2008 to $26,409 in 2009.
Are you still surprised by anger at the polls? Might these numbers explain the seeming willingness of voters to try anything that looks different? Rising inequality, falling incomes and increasing poverty are very pronounced. When the data comes in next year for 2010, it is likely to show us that the period from 2008 through 2010 witnessed a historic increase in poverty and inequality in the US. Our massive budget deficits have been directed in ways that lower poverty, increase employment or reduce inequality. Surely, these numbers would have been worse absent many programs. That is true and valid. However, it is way too hard out there to be smug about how much worse it could have been. Yes, it could be worse. Yes, it is getting worse.
Below follows a sketch of just how bad it is- from a poverty perspective. All graphs in this article are based on the recently released census data.

It is clear that the younger you are in America, the more likely you are to live in poverty. Young Americans are nearly twice as likely to be poor as older Americans. The bar graph demonstrates this trend for African-Americans.

Being American gives you a one in seven chance of being poor. Being young raises this chance to one in four. Further, being black in America means a one in four chance of being poor. Being young and black raises your chance of being poor up to one in 2.5.
Education played a role in 2009 poverty rates, as indicated in the graph below. Dropping out of high school puts you on a path to a one in four chance of poverty. Finishing college drops your chance of poverty in 2009 to one in 25.

2009 American Consumer Survey: Selected Economic Characteristics. US Census Bureau.
Urban populations were particularly hard hit. More than 18 percent (18.7 percent) of Americans living in major cities spent 2009 living in poverty, while 27.8 percent of Americans living in major cities and under 18 years of age spent 2009 living in poverty. That means that nearly one in three young, urban Americans were poor last year.
Female-headed households fared especially badly: more than one in three lived in poverty in 2009. More than 17 percent (17.3 percent) of these female-headed households lived in extreme poverty – earning less than 50 percent of the federal poverty level.
BRIC nations urging UN to counter unilateral anti-Iran sanctions
Press TV – September 22, 2010
Brazil, Russia, India and China (BRIC) are urging the UN to reproach countries that impose unilateral sanctions not approved by the UN Security Council, Brazilian foreign minister says.
“We’re beginning to have some political coordination on General Assembly resolutions,” Celso Amorim told Reuters on Tuesday, referring to the coordination among the four nations which make the BRIC group.
“In some cases we’re even against multilateral sanctions, so for sure unilateral sanctions aren’t welcome because they’re outside the UN system,” said Amorim, who is in New York to attend the opening of the UN General Assembly. He further added that the BRIC members discussed the proposed resolution in a meeting of foreign ministers on Tuesday in New York.
According to Reuters, a resolution in this regard, if approved by the UN General Assembly, could lead to depletion of the legitimacy of additional sanctions imposed by the United States and other Western powers against Iran’s nuclear program.
Following the imposition of US-engineered UN Security Council sanctions against the Islamic Republic in June, the United States and the European Union imposed further unilateral sanctions on Tehran over its nuclear program.
Fearing those tensions could escalate into war, Brazil had earlier tried to evade the additional sanctions, intermediating a nuclear fuel swap deal between Iran and Turkey. That agreement was largely ignored by the United States.
Commenting on relations between Brazil and the US, Amorim said relations between the two countries remain good, though they disagree on strategy to prevent Iran’s access to nuclear weapons.
“Government relations remain very good, but in some issues we’re going to disagree,” he concluded.
The progressive dilemma
By Nick Egnatz | Online Journal | September 20, 2010
A self-described representative democracy in which the only two political parties are both funded and controlled by elite corporate interests is a contradiction in terms. Control of the population through government propaganda and a monopoly corporate media have made the domination of the American working class and poor by the wealthy corporate elite consensual. The enormity of the crime against true democratic values is so complete that substantive reform of the present system is an impossibility.
A dilemma is a situation in which one is forced to choose between equally distasteful options. That has always been our consignment as Americans when we venture to the polls (either vote for a wishy-washy Democrat or let the even worse Republican win). Every two years we are told that the fate of our democracy rests on our decision. Well it doesn’t because we don’t have a democracy, representative or otherwise. We have a plutocracy (rule by the wealthy). Our two political parties answer out of necessity to the corporate world. No one represents the people and the monopoly corporate media will not allow for a discussion of democratic alternatives.
The chickens have come home to roost from the last 30 years of economic neoliberal globalization policies championed by both political parties. Supply side economics of massive tax cuts for the wealthy and deregulation of the very modest checks on American capitalism necessitated by the Great Depression have made us the most unequal industrial democracy on earth. Imperial wars of aggression and massive bailouts of the very speculators who engineered the financial collapse leading to the Great Recession have allowed both corporate parties to take the stance that there is no money left for the people’s needs. This is poppycock. How can a consumer driven economy recover if the working class and poor have no jobs or money?
To cut spending on social programs with political cover, Obama came up with the brilliant idea of a budget deficit commission (National Commission on Fiscal Responsibility and Reform) made up of bipartisan hacks from both our two corporate parties, representatives from the corporate world of greed and a single union president. Green Party and socialists need not apply and in fact there are no even mildly progressive Democrats (an oxymoron if there ever was one) on the commission. The commission is not a result of legislation from our Congress. It was formed by Executive Order. This is the way dictators govern, but that’s another issue. The commission is charged to cut the Budget Deficit by cutting social programs only and leaving the military spending intact. If and when 14 of the commission’s 18 members agree on policy it will go straight to Congress for a vote with no amendments allowed.
Co-chairman of the commission Alan Simpson, former Republican Senator from Wyoming received some notoriety recently by referring to seniors on Social Security as “lesser people,” calling Social Security a “cow with 310 million tits” and asking the question of Vietnam veterans “what have they done for us lately?’ None of this bothered our President enough to ask for Simpson’s resignation. Their recommendation is due in December, after the midterm election.
We are expected to accept the government propaganda that the unemployment rate is 9.6 percent, when that figure does not include those no longer receiving or who never received unemployment compensation, part time workers desiring full time work or workers disdainfully referred to as having given up looking for work. Including all these would bring the unemployment figure to 22 percent. But that still doesn’t count those working for less than a livable wage, this would easily bring the figure well beyond the 30 percent range. This assault on the working class has been the goal of the neoliberal globalization policy accepted as gospel by both corporate political parties since Ronald Reagan started selling it in the 70’s and 80’s when he set out to save the country from the scourge of a prosperous working class. The Great Communicator pushed his dogma of bad government/good corporations with the same smile he used to push Twenty Mule Team Borax soap to TV viewers years earlier.
More than 3 million families have already been foreclosed and torn from their homes. Another 11 million families are “underwater” (owing more that the home is worth). Research firm First American Core Logic reports that Nevada with 65 percent of home mortgages underwater, Arizona with 48 percent, Florida with 45 percent, Michigan with 37 percent and California with 35 percent lead the nation in this foreboding statistic.
The Republicans propose fiscal austerity for the poor and working class and continued tax cuts for the wealthy corporate class to find our way our of the Great Recession. Obama and the Democrats say that economic growth will do the trick. Both so called solutions are illogical. We are expected to believe that if the big bad bankers would just pretty please start loaning money to businesses, the economy will start humming and everything will be hunky dory?
I’m not an economist, but I have been a small businessman and I have been told on more than one occasion that I have half a brain. The road to recovery is both simple and difficult. For businesses to thrive, for the economy to hum, the business owners simply need customers with money in their pockets. The first step is to put our citizens back to work at a livable wage and the economy will flourish. It will be difficult, to the point of impossibility, for corporate politicians to consider the people at the bottom first, but that is what needs to be done.
We are told that the fall elections are for the control of our country. Nothing could be further from the truth. We are told that we cannot allow the Republican Party of No to win Congress, yet the Democrats have controlled Congress for four years, the White House for two and there has been no challenge to the draconian policies of social spending cuts, endless imperial war and progressively greater and greater inequality. All now completely part and parcel of the fabric of a nation once founded on the single statement that “all men are created equal.” Regardless of which party wins and controls Congress, elite domination of the poor and working class will continue.
Understand that the system is beyond redemption. Recognize that we have exported the cancer of elite domination through globalization across the globe and that the struggle belongs to all the poor and working people of the world. Boycott elections that give credibility to this monstrous system of inequality and class domination. Organize on the basis of class and struggle for the equality that was promised in 1776.
Or you can support the Democratic Party and continue to see more of the same; continued wars, huge military budgets, depressed home prices, foreclosures, abandoned underwater mortgages, progressively greater and greater inequality and Depression Era unemployment. All done while the Democrats complain that they would like to change things, but that they just don’t have the votes or the heart or the balls. The last two they won’t admit to, but we all know better.
I’m not painting a pretty picture, because it isn’t pretty and wishing it was better won’t make it so. Voting for third party candidates, independents or so called progressive Democrats only serves to give legitimacy to an undemocratic system. The first step toward a true participatory democracy is to vocally and publicly boycott elections and renounce the American system of money controlled policies and politics through the two corporate political parties.
Right-wingers and liberal Democrats both love to say that I advocate for some kind of nebulous utopian dream. If you want nebulous from the right tune in to Glen Beck and Sarah Palin’s call for restoring America’s honor. If you want the equivalent from the Democratic Party listen to Obama’s calls for hope and change. Both appeals are long on rhetoric and bereft of specific steps to alleviate the misery corporate America and their two lackey political parties have trickled down on the poor and working class.
This socialist utopian will instead give specific plans for a new birth of democracy in America:
- 100 percent federal funding for all national elections. Under the proposal below this figure will become minuscule.
- No election commercials allowed. This just allows money to pollute politics. Instead require all media outlets to publish and broadcast periodic side by side statements of all the candidates positions on the various issues. Mandate debates in which all the candidates get a chance to state their positions on the issues.
- Require run-off elections if no candidate polls more than 50 percent of vote. This will facilitate the growth of alternative parties.
- Either eliminate the anti democratic U.S. Senate or require it to do away with the filibuster rule which allows 41 Senators from the smallest states, representing only 11 percent of the U.S. population to halt all legislation with the exception of certain budget votes.
- Return U.S. income tax rate on the most wealthy Americans to 90 percent for their excess income over $1 million. For 45 years (1935-1980) the top tax rate was between 70-94 percent. It is now 35 percent and the ever widening gap between rich and poor has made the U.S. the equivalent of a banana republic.
- Institute a financial transaction tax on all financial transactions such as stock sales.
- Cancel all free trade agreements and renegotiate into fair trade agreements in which tariffs are re-instituted to even the playing field when dealing with nations with substandard wages and environmental regulations. This is in line with the policy instituted by the first Secretary of the Treasury Alexander Hamilton, done at the behest of George Washington and carried forward for almost two centuries. That is until the neo-liberal globalization crowd made their first appearance after WWII and in the last three decades especially have managed to lower tariffs to an average of 2 percent. The rationale behind tariffs is to level the playing field for our workers. If country A has the same wage rate and basic environmental safeguards as we do, a free trade agreement with them is in order. But if country B has a wage rate much lower than ours and pays little attention to environmental safeguards, then we should have tariffs reflecting these differences. Free trade is fine with equal trading partners, but not with countries paying slave wages and polluting the environment like China.
- Give workers a seat at the table on all corporate boards with veto privileges as a protection for the American people from corporate dominance.
- Do away with the minimum wage and institute a living wage guaranteeing all workers a wage allowing for basic necessities. This will vary with the cost of living in different areas and individual family commitments, but for a single worker with no other dependents in an average area it would presently be about $15/hour.
- Institute a massive program similar to the WPA to put all the unemployed to work at a living wage. There is much work to do, let us do it. Our cities need rebuilding, seniors need care, single parents need parenting help, homes need to be made energy efficient, infrastructure needs repair.
- For small businesses that show through their tax returns an inability to pay their workers the living wage, have the federal government make up the difference until such time as the small business can support its workers on its own.
- Abolish the Federal Reserve Bank and institute a national bank with the power to create money presently given to the Federal Reserve. As the population and economy grows there is a need to create money. If this is not done, it causes deflation and things get progressively cheaper. While that might sound nice at first glance, not creating money would be every bit the disaster that high inflation can be. Imagine buying a home with a mortgage and watching the price drop every year. That’s deflation. We now have that with home prices, but for other reasons. Anyway, the new national bank will have the power to create money and the profit from creating this money will benefit all the people instead of the present banking class.
- The mortgage crisis must be addressed. The megabanks and Wall Street brought it on and should be required to adjust all mortgage balances down by the local percentage that home prices have dropped. The federal government might then consider not prosecuting those responsible for the crisis.
- Capitalism requires continual growth. This is at odds with the earth’s environment. We need to create a sustainable economy which does not wreak havoc with the earth’s delicate ecosystems. Economic growth is good only when it is environmentally sustainable.
- Just as the poor and working class are required to pay social security tax on all their income, require the wealthy to do the same.
- Recognize that healthcare is a human right and immediately institute either 100 percent government single payer healthcare for all or have government take over the healthcare apparatus and be both the employer and the payer of all healthcare bills.
- End the wars for U.S. Empire overseas. Close our 700 overseas military bases. Cut the total military budget (now in excess of $1 trillion) in half and then half again.
- Disband the Central Intelligence Agency and apologize to the people of all the countries in which our CIA engineered coups to overthrow democratically elected governments. A partial list would include Chile, Brazil, Nicaragua, Honduras, El Salvador, Haiti, Cuba, Venezuela, Greece, Congo and Iran.
- End military aid to Israel and break off diplomatic relations with them until such time as they agree to abandon all the illegal settlements in the West Bank, tear down the apartheid wall, end the criminal blockade of Gaza and finally allow the Palestinian people a free and independent state based on the 1967 borders that are recognized by the international community of nations.
- The House of Representatives Judiciary Committee Democratic Minority Report in 2005 declared that there was a prima facie case that the Bush Administration broke at least seven federal and international laws in taking us into war in Iraq. If we are to be a country of laws, Bush, Cheney, Rice, Rumsfeld, Powell etc. must be investigated and prosecuted.
- Those responsible at the highest level for our policy of torture must be prosecuted.
- Equal diligence should be given to investigating and prosecuting the financial machinations behind the mortgage derivative bundling and trading scams. If they agree to reduce all mortgages by the local percentage drop in value, rework terms for those facing foreclosure, put already foreclosed families back in their homes and donate the rest of their ill gotten gain to charity, we might want to consider not prosecuting.
- The 9/11 Commission Investigation and Report was a complete whitewash. How can there be independence in the investigation when the President is allowed to appoint all the members of the commission? The American people are owed the truth and an independent investigation is absolutely necessary if we are to call ourselves a nation of laws.
- A democracy cannot exist without an informed citizenry. Media purveyors must be required to present the full spectrum of news and opinion.
Politicians from both political parties will avoid these issues like the plague. The question is, should you? Or are you content to support politicians who use soaring rhetoric in describing the plight of our people and then line up in support of corporate friendly legislation that continues the race to the bottom for the poor and working class of America? Will your vote for Congress and the U.S. Senate go to a Democratic candidate who supports not a single one of the above proposals? If the answer is yes and you consider yourself a progressive or liberal, what exactly does that mean?
We can’t fix this system by voting, petitioning, marching or lobbying. We have to change the system. The first step is to call the system what it is; monstrous, criminal and undemocratic. The next step is to refuse to participate in elections and to not be bashful in telling others why. This won’t save the world now, but it’s the only hope for the future.
IMPERIALISM AND IMPERIAL BARBARISM
By JAMES PETRAS | My Catbird Seat | September 19, 2010
Imperialism, its character, means and ends has changed over time and place. Historically, western imperialism, has taken the form of tributary, mercantile, industrial, financial and in the contemporary period, a unique ‘militarist-barbaric’ form of empire building. Within each ‘period’, elements of past and future forms of imperial domination and exploitation ‘co-exist’ with the dominant mode. For example , in the ancient Greek and Roman empires, commercial and trade privileges complemented the extraction of tributary payments. Mercantile imperialism, was preceded and accompanied initially by the plunder of wealth and the extraction of tribute, sometimes referred to as “primitive accumulation”, where political and military power decimated the local population and forcibly removed and transferred wealth to the imperial capitals. As imperial commercial ascendancy was consolidated, manufacturing capital increasingly emerged as a co-participant; backed by imperial state policies manufacturing products destroyed local national manufacturers gaining control over local markets. Modern industrial driven imperialism, combined production and commerce, both complemented and supported by financial capital and its auxiliaries, insurance, transport and other sources of “invisible earnings”.
Under pressure from nationalist and socialist anti-imperialist movements and regimes, colonial structured empires gave way to new nationalist regimes. Some of which restructured their economies, diversifying their productive systems and trading partners. In some cases they imposed protective barriers to promote industrialization. Industrial-driven imperialism, at first opposed these nationalist regimes and collaborated with local satraps to depose industrial oriented nationalist leaders. Their goal was to retain or restore the “colonial division of labor” – primary production exchanged for finished goods. However, by the last third of the 20th century, industrial driven empire building, began a process of adaptation, “jumping over tariff walls”, investing in elementary forms of ‘production’ and in labor intensive consumer products. Imperial manufacturers contracted assembly plants organized around light consumer goods (textiles, shoes, electronics).
Basic changes in the political, social and economic structures of both the imperial and former colonial countries, however, led to divergent imperial paths to empire-building and as a consequence contrasting development performances in both regions.
Anglo-American financial capital gained ascendancy over industrial, investing heavily in highly speculative IT, bio-tech, real estate and financial instruments. Germany and Japanese empire builders relied on upgrading export-industries to secure overseas markets. As a result they increased market share, especially among the emerging industrializing countries of Southern Europe, Asia and Latin America. Some former colonial and semi-colonial countries also moved toward higher forms of industrial production, developing high tech industries, producing capital and intermediate as well as consumer goods and challenging western imperial hegemony in their proximity.
By the early 1990’s a basic shift in the nature of imperial power took place. This led to a profound divergence between past and present imperialist policies and among established and emerging expansionist regimes.
Past and Present Economic Imperialism
Modern industrial-driven empire building (MIE) is built around securing raw materials, exploiting cheap labor and increasing market share. This is accomplished by collaborating with pliant rulers, offering them economic aid and political recognition on terms surpassing those of their imperial competitors. This is the path followed by China. MIE eschews any attempt to gain territorial possessions, either in the form of military bases or in occupying “advisory” positions in the core institutions of the coercive apparatus. Instead, MIEs’ seek to maximize control via investments leading to direct ownership or ‘association’ with state and/or private officials in strategic economic sectors. MIEs’ utilize economic incentives in the way of economic grants and low interest concessionary loans. They offer to build large scale long term infrastructure projects-railroads, airfields, ports and highways. These projects have a double purpose of facilitating the extraction of wealth and opening markets for exports. MIEs also improve transport networks for local producers to gain political allies. In other words MIEs like China and India largely depend on market power to expand and fight off competitors. Their strategy is to create “economic dependencies” for long term economic benefits.
In contrast imperial barbarism grows out of an earlier phase of economic imperialism which combined the initial use of violence to secure economic privileges followed by economic control over lucrative resources.
Historically, economic imperialism (EI) resorted to military intervention to overthrow anti-imperialist regimes and secure collaborator political clients. Subsequently, EI frequently established military bases and training and advisory missions to repress resistance movements and to secure a local military officialdom responsive to the imperial power. The purpose was to secure economic resources and a docile labor force, in order to maximize economic returns.
In other words, in this ‘traditional’ path to economic empire building the military was subordinated to maximizing economic exploitation. Imperial power sought to preserve the post colonial state apparatus and professional cadre but to harness them to the new imperial economic order. EI sought to preserve the elite to maintain law and order as the basic foundation for restructuring the economy. The goal was to secure policies to suit the economic needs of the private corporations and banks of the imperial system. The prime tactic of the imperial institutions was to designate western educated professionals to design policies which maximized private earning. These policies included the privatization of all strategic economic sectors; the demolition of all protective measures favoring local producers (“opening markets”); the implementation of regressive taxes on local consumers, workers and enterprises while lowering or eliminating taxes and controls over imperial firms; the elimination of protective labor legislation and outlawing of independent class organizations.
In its heyday western economic imperialism led to the massive transfer of profits, interest, royalties and ill begotten wealth of the native elite from the post-colonial countries to the imperial centers. As befits post-colonial imperialism the cost of administrating these imperial dependencies was borne by the local workers, farmers and employees.
While contemporary and historic economic imperialism have many similarities, there are a few crucial differences. For example China, the leading example of a contemporary economic imperialism, has not established its “economic beach heads” via military intervention or coups, hence it does not possess ‘military bases’ nor a powerful militarist caste competing with its entrepreneurial class in shaping foreign policy. In contrast traditional Western economic imperialism contained the seeds for the rise of a powerful militarist caste capable, under certain circumstances, of affirming their supremacy in shaping the policies and priorities of empire building.
This is exactly what has transpired over the past twenty years, especially with regard to US empire building.
The Rise and Consolidation of Imperial Barbarism
The dual processes of military intervention and economic exploitation which characterized traditional Western imperialism gradually shifted toward a dominant highly militarized variant of imperialism. Economic interests, both in terms of economic costs and benefits and global market shares were sacrificed in the pursuit of military domination.
The demise of the USSR and the virtual reduction of Russia to the status of a broken state, weakened states allied to it. They were “opened” to Western economic penetration and became vulnerable to Western military attack.
President Bush (senior) perceived the demise of the USSR as an ‘historic opportunity’ to unilaterally impose a unipolar world. According to this new doctrine the US would reign supreme globally and regionally. Projections of US military power would now operate unhindered by any nuclear deterrence. However, Bush (senior) was deeply embedded in the US petroleum industry. Thus he sought to strike a balance between military supremacy and economic expansion. Hence the first Iraq war 1990-91 resulted in the military destruction of Saddam Hussein’s military forces, but without the occupation of the entire country nor the destruction of civil society, economic infrastructure and oil refineries. Bush (senior) represented an uneasy balance between two sets of powerful interests: on the one hand, petroleum corporations eager to access the state owned oil fields and on the other the increasingly powerful militarist zionist power configuration within and outside of his regime. The result was an imperial policy aimed at weakening Saddam as a threat to US clients in the Gulf but without ousting him from power. The fact that he remained in office and continued his support for the Palestinian struggle against the Jewish state’s colonial occupation profoundly irritated Israel and its zionist agents in the US.
With the election of William Clinton, the ‘balance’ between economic and military imperialism shifted dramatically in favor of the latter. Under Clinton, zealous zionists were appointed to many of the strategic foreign policy posts in the Administration. This ensured the sustained bombing of Iraq, wrecking its infrastructure. This barbaric turn was complemented by an economic boycott to destroy the country’s economy and not merely “weaken” Saddam. Equally important, the Clinton regime fully embraced and promoted the ascendancy of finance capital by appointing notorious Wall Streeters (Rubin, Summers, Greenspan et al.) to key positions, weakening the relative power of oil, gas and industrial manufacturers as the driving forces of foreign policy. Clinton set in motion the political ‘agents’ of a highly militarized imperialism, committed to destroying a country in order to dominate it.
The ascent of Bush (junior) extended and deepened the role of the militarist-zionist personnel in government. The self-induced explosions which collapsed the World Trade Towers in New York served as a pretext to precipitate the launch of imperial barbarism and spelled the eclipse of economic imperialism.
While US empire building converted to militarism, China accelerated its turn toward economic imperialism. Their foreign policy was directed toward securing raw materials via trade, direct investments and joint ventures. It gained influence via heavy investments in infrastructure, a kind of developmental imperialism, stimulating growth for itself and the “host” country. In this new historic context of global competition between an emerging market driven empire and an atavistic militarist imperial state, the former gained enormous economic profits at virtually no military or administrative cost while the latter emptied its treasury to secure ephemeral military conquests.
The conversion from economic to militarist imperialism was largely the result of the pervasive and ‘deep’ influence of policymakers of zionist persuasion. Zionist policymakers combined modern technical skills with primitive tribal loyalties. Their singular pursuit of Israel’s dominance in the Middle East led them to orchestrate a series of wars, clandestine operations and economic boycotts crippling the US economy and weakening the economic bases of empire building.
Militarist driven empire building in the present post-colonial global context led inevitably to destructive invasions of relatively stable and functioning nation-states, with strong national loyalties. Destructive wars turned the colonial occupation into prolonged conflicts with resistance movements linked to the general population. Henceforth, the logic and practice of militarist imperialism led directly to widespread and long-term barbarism-the adoption of the Israeli model of colonial terrorism targeting an entire population. This was not a coincidence. Israel’s zionist zealots in Washington “drank deeply” from the cesspool of Israeli totalitarian practices, including mass terror, house demolitions, land seizures, overseas special force assassination teams, systematic mass arrests and torture. These and other barbaric practices, condemned by human rights organizations the world over, (including those in Israel), became routine practices of US barbaric imperialism.
The Means and Goals of Imperial Barbarism
The organizing principle of imperial barbarism is the idea of total war. Total in the sense that (1) all weapons of mass destruction are applied; (2) the whole society is targeted; (3) the entire civil and military apparatus of the state is dismantled and replaced by colonial officials, paid mercenaries and unscrupulous and corrupt satraps. The entire modern professional class is targeted as expressions of the modern national-state and replaced by retrograde religious-ethnic clans and gangs, susceptible to bribes and booty-shares. All existing modern civil society organizations, are pulverized and replaced by crony-plunderers linked to the colonial regime. The entire economy is disarticulated as elementary infrastructure including water, electricity, gas, roads and sewage systems are bombed along with factories, offices, cultural sites, farms and markets.
The Israeli argument of “dual use” targets serves the militarist policymakers as a justification for destroying the bases of a modern civilization. Massive unemployment, population displacement and the return to primitive exchanges characteristic of pre-modern societies define the “social structure”. Educational and health conditions deteriorate and in some cases become non-existent. Curable diseases plague the population and infant deformities result from depleted uranium, the pre-eminent weapon of choice of imperial barbarism.
In summary the ascendancy of barbarous imperialism leads to the eclipse of economic exploitation. The empire depletes its treasury to conquer, destroy and occupy. Even the residual economy is exploited by ‘others’: traders and manufacturers from non-belligerent adjoining states. In the case of Iraq and Afghanistan that includes Iran, Turkey, China and India.
The evanescent goal of barbarous imperialism is total military control, based on the prevention of any economic and social rebirth which might lead to a revival of secular anti-imperialism rooted in a modern republic. The goal of securing a colony ruled by cronies, satraps and ethno-religious warlords – willing givers of military bases and permission to intervene – is central to the entire concept of military driven empire building. The erasure of the historical memory of a modern independent secular nation-state and the accompanying national heritage becomes of singular importance to the barbarous empire. This task is assigned to the academic prostitutes and related publicists who commute between Tel Aviv, the Pentagon, Ivy league universities and Middle East propaganda mills in Washington.
Results and Perspectives
Clearly imperial barbarism (as a social system) is the most retrograde and destructive enemy of modern civilized life. Unlike economic imperialism it does not exploit labor and resources, it destroys the means of production, kills workers, farmers and undermines modern life.
Economic imperialism is clearly more beneficial to the private corporations; but it also potentially lays the bases for its transformation. Its investments lead to the creation of a working and middle class capable of assuming control over the commanding heights of the economy via nationalist and/or socialist struggle. In contrast the discontent of the ravaged population and the pillage of economies under imperial barbarism, has led to the emergence of pre-modern ethno-religious mass movements, with retrograde practices, (mass terror, sectarian violence etc.). Theirs is an ideology fit for a theocratic state.
Economic imperialism with its ‘colonial division of labor’, extracting raw materials and exporting finished goods, inevitably will lead to new nationalist and perhaps later socialist movements. As EI undermines local manufacturers and displaces, via cheap industrial exports, thousands of factory workers, movements will emerge. China may seek to avoid this via ‘plant transplants’. In contrast barbaric imperialism is not sustainable because it leads to prolonged wars which drain the imperial treasury and injury and death of thousands of American soldiers every year. Unending and unwinable colonial wars are unacceptable to the domestic population.
The ‘goals’ of military conquest and satrap rule are illusory. A stable, ‘rooted’ political class capable of ruling by overt or tacit consent is incompatible with colonial overseers. The ‘foreign’ military goals imposed on imperial policymakers via the influential presence of zionists in key offices have struck a mighty blow against the profit seeking opportunities of American multi-nationals via sanctions policies. Pulled downward and outward by high military spending and powerful agents of a foreign power, the resort to barbarism has a powerful effect in prejudicing the US economy.
Countries looking for foreign investment are far more likely to pursue joint ventures with economic driven capital exporters rather than risk bringing in the US with all its military, clandestine special forces and other violent baggage.
Today the overall picture is grim for the future of militarist imperialism. In Latin America, Africa and especially Asia, China has displaced the US as the principal trading partner in Brazil, South Africa and Southeast Asia. In contrast the US wallows in unwinable ideological wars in marginal countries like Somalia, Yemen and Afghanistan. The US organizes a coup in tiny Honduras, while China signs on to billion dollar joint ventures in oil and iron projects in Brazil and Venezuela and an Argentine grain production. The US specializes in propping up broken states like Mexico and Columbia, while China invests heavily in extractive industries in Angola, Nigeria, South Africa and Iran. The symbiotic relationship with Israel leads the US down the blind ally of totalitarian barbarism and endless colonial wars. In contrast China deepens its links with the dynamic economies of South Korea, Japan, Vietnam, Brazil and the oil riches of Russia and the raw materials of Africa.
James Petras is a Bartle Professor (Emeritus) of Sociology at Binghamton University, New York. He is the author of 64 books published in 29 languages, and over 560 articles in professional journals, including the American Sociological Review, British Journal of Sociology, Social Research, Journal of Contemporary Asia, and Journal of Peasant Studies. He has published over 2000 articles. His latest book is War Crimes in Gaza and the Zionist Fifth Column in America (Atlanta:Clarity Pres 2010)
Turkey to ‘triple’ trade volume with Iran
Press TV – September 16, 2010
Turkish Prime Minister Recep Tayyip Erdogan says the country plans to triple its trade volume with Iran within five years, stressing the importance of ties with Iran.
“Our bilateral trade ties have reached $10 billion … when we complete our preferential trade agreement we can reach a bilateral trade volume of $30 billion in five years,” Reuters quoted Erdogan as saying on Thursday.
“Why can’t we establish a mechanism of unrestricted trade with Iran similar to the one we have with Europe? I personally don’t see any reason why we should not be able to accomplish this,” he said in the Iran-Turkey Business Forum, Anatolia News Agency reported.
“Just as we are Iran’s gate into Europe, Iran is our most important gate into Asia,” Erdogan said, adding that economic cooperation between the two countries could be further expanded, IRNA reported.
The Turkish prime minister said the “geographic proximity” offers the two countries unique opportunities to improve their “commercial and economic ties.”
Earlier Thursday, Iranian First Vice President Mohammad-Reza Rahimi, who also attended the forum, stressed the importance of expanding ties between the two countries’ private sectors.
“We intend to promote economic cooperation with Turkey, Syria, Iraq and other countries in the region,” he said.
Saudi splurges on weapons … for what?
By Teymoor Nabili | Al-Jazeera | September 14th, 2010
Saudi Arabia is about to buy another $60bn worth of military hardware from the US, and even The Guardian is dutiful in parroting, without question, the accepted western narrative :
The sale, under negotiation since 2007, is aimed mainly at bolstering Saudi defenses against Iran, which the US suspects will achieve a nuclear weapons capability within the next few years. The transfer of advanced technology, mainly planes, is to provide Saudi Arabia with air superiority over Iran.
Ignoring the fact that miltary aircraft (which form the bulk of the deal as we know it) are pretty much useless against a nuclear missile, especially one that does not exist, $60bn buys a mind boggling amount of firepower, so that must mean that Saudi Arabia’s military capacity right now is woefully insufficient compared to Iran’s, right?
Er, no.
Saudi military spending already dwarfs Iran’s by a factor of six. Indeed, by head of population, Saudi is the world’s biggest purchaser of military hardware.
Global Firepower has a direct comparison of the two nations’ military strengths, and it turns out that Iran’s military is only superior in terms of manpower numbers.
So if Iran’s intention is to send waves of soldiers marching across the desert, then maybe Saudi has something to fear.
But when it comes to “air-based weapons”, Global Firepower puts the relative numbers (before this deal) at Saudi 453, Iran 84. (Bear in mind also that Iran’s aircraft are widely described as museum pieces by military analysts, because the sanctions mean that Iran has no access to spare parts or modern technology).
So why does Saudi need 84 new F-15 fighter jets, 70 upgraded F-15s, 70 Apaches, 72 Black Hawks and 36 “Little Birds”, just to fight a land army?
And when you consider the reality that Saudi has the full support of all the US military bases in the region, the suggestion that Riyadh has something to fear from Tehran is laughable.
So if the numbers don’t add up, what about the politics? Well, the suggestion that Iran is keen to invade Saudi Arabia makes even less sense than the suggestion that Tehran intends to attack Israel, and the Arab world knows it.
As King Abdullah of Jordan said recently, the Arab world is much more concerned about the Israeli-Palestinian conflict than any Iran issue.
And, as a major survey of the Arab public opinion found recently, the Arab majority not only agrees with King Abdullah but is in fact very sympathetic of Iran’s right to nuclear technology, with a majority saying a nuclear-armed Iran may in fact be a good thing for the region.
Amjad Atalla of New America Foundation has an excellent summary of this whole debate here.
And the American Foreign Policy Project covers many of the myths and nuances of the military and security debates concerning Iran here.
So, if the mainstream media have missed the point, then what is really going on?
Well, with America suffering it’s worst recession in 60 years, the biggest arms contract ever signed would certainly be a welcome boost to earnings in the military industrial sector.
And as I blogged a year ago, Saudi Arabia has always been keen to buy as much favor in Washington as it can, because it’s concerned that any hint of warming relations between DC and Tehran would almost by definition be a threat to Riyadh’s regional hegemony.
States test whether public pension benefits given can be taken away
By Stephen C. Fehr | Stateline | August 10, 2010
 State legislators are beginning to challenge one of the ironclad tenets of public pension policy: that states cannot legally reduce pension benefits for current and future retirees. Lawmakers in Colorado, Minnesota and South Dakota voted earlier this year to limit cost-of-living increases they previously had promised to thousands of current and future retirees, who courts historically have protected from benefit reductions. Not surprisingly, retirees in each state have filed lawsuits asking judges to restore their annual benefit increases to what they were previously.
Lawmakers, state retirement systems, public employee unions and others in the pension policy arena are closely watching the outcome of the legal challenges. If the courts do not reinstate the retirees’ benefits, a flood of states could follow the lead of Colorado, Minnesota and South Dakota. The reverse also would be true. “If the plaintiffs are successful, it may discourage legislators in other states from attempting to diminish benefits,” says Keith Brainard, research director at the National Association of State Retirement Administrators.
California Governor Arnold Schwarzenegger and New Jersey Governor Chris Christie, among other officials, favor scaling back pension benefits already promised to current employees and retirees. And a lively debate on the issue is underway in Illinois, where lawmakers reduced the cost-of-living adjustment for newly hired workers. Interest is keen everywhere: Lawmakers from around the country packed a session on modifying public pension benefits at the recent annual meeting of the National Conference of State Legislatures in Louisville.
Up to now, states trying to trim the rising cost of worker retirement benefits have taken the legally safer — and politically easier — approach of targeting benefit cuts at newly hired employees. Steps states have taken this year include increasing the amount employees contribute toward their own pensions, raising the retirement age and adjusting the formula upon which benefits are based.
But many state lawmakers and pension administrators have concluded that cutting benefits for new employees alone will not save enough money in the short term to keep pension plans solvent over time. So they are searching for ways to zero in on the benefits of current retirees and employees.
Colorado lawmakers, facing projections showing the state’s pension system would run out of money within 30 years, approved a package of benefit reductions that lowered the annual 3.5 percent cost-of-living increase for retirees in 2010 to zero. In future years, the increase will be set at 2 percent, barring another sharp decline in investments. If the changes stand, the average retiree would lose more than $165,000 in benefits over the next 20 years, the retirees say in court papers.
South Dakota reduced the cost-of-living increase from 3.1 percent to 2.1 percent this year; future-year amounts will be tied to how well the system’s investments perform in the market. Minnesota eliminated a 2.5 percent cost-of-living increase and set it at between 1 and 2 percent for its different employee pension funds.
Case law and state constitutions
History is on the employees’ side. State statutes, constitutions and case law consistently define a public pension as a contract between the state and its employees that cannot be impaired. For example, Alaska’s state constitution makes it clear that “membership in employee retirement systems of the state or its political subdivisions shall constitute a contractual relationship. Accrued benefits of these systems may not be diminished or impaired.” Eight other states protect workers in their constitutions. They are Arizona, Hawaii, Illinois, Louisiana, Michigan, New Mexico, New York and Texas.
In states without constitutional guarantees — Colorado, Minnesota and South Dakota fall into this category — statutes and court cases consider retirement benefits an unbreakable contract between the state and workers. That same protection is in the contract clause of the U.S. Constitution, which says: “No state shall … pass any … law impairing the obligations of contracts.”
Courts have determined that cost-of-living increases, which keep pension income on pace with inflation, are part of a worker’s benefits that cannot be diminished. (Generally, increasing benefits faces no legal hurdles.) The principle of safeguarding the purchasing power of pension income through a cost-of-living adjustment is well established. Social Security, the federal government’s retirement program, instituted automatic annual cost-of-living increases in 1975. The amount of the increase has averaged about 3.3 percent a year, although for the first time in 2010, there was no increase because the consumer price index did not rise.
The Colorado, Minnesota and South Dakota lawmakers are hoping that the courts will agree that the current financial turmoil facing states imperils public pension systems as never before and calls for a new approach. If legislatures are not permitted to cut retirement costs now, the argument goes, the ability of the public pension systems to pay future benefits will be jeopardized.
“If we don’t reduce these automatic pension increases, the entire fund is poised to go bankrupt,” Republican Josh Penry, minority leader of the Colorado state Senate, told the Denver Post. “Think United [Airlines]. Think GM. That didn’t work out well for the company or the retirees.”
Attorneys for the states say in court filings that limiting cost-of-living increases was justified, and actuarily necessary. “There can be no dispute that preserving the solvency of PERA [The Colorado Public Employees’ Retirement Association] is a legitimate governmental interest,” Colorado officials argue. Minnesota’s pension legislation “was reasonable and necessary to maintain and restore the financial stability of Minnesota’s public pension plans,” say the state’s pleadings.
Managing market swings
Although Colorado lawmakers and state pension officials blame much of the retirement fund’s current financial troubles on investment losses suffered during the 2007-09 recession — the median decline for funds nationally was 25 percent in 2008 — the truth is that Colorado lawmakers failed to make their annually required contributions to state pension funds in good times and bad. They also boosted retiree benefits without considering future costs.
Colorado’s pension fund was fully funded in 2000. Eight years later, before the recession hit, Colorado fell to 70-percent funded and was heading down further, according to a report released in February by the Pew Center on the States, which publishes Stateline. Most pension specialists recommend a funding level of 80 percent or higher.
Minnesota lawmakers also slid on their pension fund payments. Their pension system’s funding level dropped from 101 percent in 1999 to 81 percent in 2008.
“The Legislature was cutting off funds and starving the pension system,” says Stephen Pincus, a Pittsburgh attorney representing the retirees in all three states. “They shouldn’t now be able to cry there’s no money in the pension system. They had a large hand in creating the crisis.”
South Dakota offers a twist. The state Legislature has been one of the best in the nation at financing its public employee pension system over the years; it was 97-percent funded in 2000 and 2008, according to the Pew report. Lawmakers even increased benefits two years ago. The state retirement system investments did lose more than 20 percent in value in 2008, but gained as much in fiscal 2010.
Pincus says that makes South Dakota’s targeting of current employees and retirees suspect. “There’s no crisis in South Dakota,” he says. “They had one bad year. So they’re going to shore up their pension fund by cutting benefits to those who already receive them?”
Rob Wylie, executive director of the South Dakota retirement system, counters that when the funding level fell to 76 percent after the 2008 losses, it triggered for the first time a state law requiring the pension system to take immediate steps to return the funding level to 100 percent. Savings gained from reducing benefits for newly hired employees would have taken too many years for the system to catch up, Wylie says. So after consulting with retirees the pension board chose to ask lawmakers to trim the cost-of-living increase.
“We could have reversed the increase in the funding formula we approved in 2008,” says Wylie. “But the retiree groups said can you find another way to slow the growth in costs without decreasing the formula? So we did.”
Asked why states are taking the risky strategy of aiming at current retirees, Robert Klausner, a Florida attorney who specializes in public pension law, says many state officials believe they have less to lose in the courtroom by challenging pension protections than taking no action at all. “The belief is that if the employer [the state] prevails, it will have been worth the political risk,” Klausner says. “And if they lose, they will be no worse off than before.” Klausner adds that legislatures are taking the politically-difficult step and letting the courts be the “bad guy” if they overturn the law. Retired judges are among the plaintiffs in Colorado and South Dakota.
The first case to be heard is the one in Minnesota, where a September 15 hearing is scheduled on a motion for summary judgment that will be filed by the state. Colorado’s Supreme Court already has sided once with retirees, saying in a 1961 ruling, “Whether it be in the field of sports or in the halls of the legislature it is not consonant with American traditions of fairness and justice to change the ground rules in the middle of the game.”
Meredith Williams, executive director of the Colorado retirement system, says he is confident the state can prove that the system’s current and future financial stress will compel the court to allow the cost-of-living rollback. “PERA has been upfront about the challenges we face,” he says.
See related stories:
Pension overhaul treats lawmakers, other state workers differently (7/29/2010)
In graying West Virginia, a mountain of retiree health bills (7/13/2010)
In some states, pension pain yields budget gains (5/20/2010)
In New Hampshire, a new way on retiree health costs (5/12/2010)
Vermont’s pension experiment (3/25/2010)
States tackling public employee retirement benefits in 2010 (2/19/2010)
—Contact Stephen C. Fehr at sfehr@pewtrusts.org.
Stateline Staff Writer John Gramlich contributed reporting to this piece. Photo illustration by Danny Dougherty, Stateline.
Chavez to open popular tourist scheme using fugitive banker’s yachts
By Patrick J. O’Donoghue | VHeadline | September 13, 2010
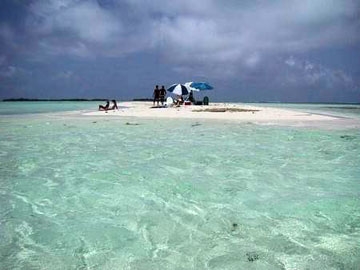
Last weekend, President Chavez announced that he would be setting up a tourist scheme from mainland Vargas State to the Orchila island using yachts belonging to a fugitive Banco Federal banker, Nelson Mezerhane.
The yachts, he suggested, will also be used to transport tourists from popular areas and barrios to the Los Roques archipelago.
The President said it was only right that people from popular areas have the chance to visit the islands and he has requested Executive Vice President Elias Jaua to speed up the purchase of a ferry that Venezuela was purchasing from Portugal.
Chavez admitted delays in acquiring the ferry.
People should be able to relax healthily, Chavez mused, stressing that it was difficult for poor people to fly by plane to Margarita island and for that reason he wanted to create a popular tourism company.
Who Rules America?
By James Petras – January 13, 2007
In the broadest and deepest sense, understanding how the US political system functions, the decisions of war and peace are taken, who gets what, how and why, requires that we address the question of ‘Who rules America?’ In tackling the question of ‘ruling’ one needs to clarify a great deal of misunderstandings, particularly the confusion between those who make governmental decisions and the socio-economic institutional parameters which define the interests to be served. ‘Ruling’ is exacting: it defines the ‘rules’ to be followed by the political and administrative decision-makers in formulating budgetary expenditures, taxes, labor and social legislation, trade policy, military and strategic questions of war and peace. The ‘rules’ are established, modified and adjusted according to the specific composition of the leading sectors of a ruling class (RC). Rules change with shifts in power within the ruling class. Shifts in power can reflect the internal dynamics of an economy or the changing position of economic sectors in the world economy, particularly the rise and decline of economic competitors.
The ‘rules’ imposed by one economic sector of the RC at a time of favorable conditions in the world economy, will be altered as new dominant economic sectors emerge and unfavorable external conditions weaken the former dominant economic sectors. As we shall describe below the relative and absolute decline of the US manufacturing sector is directly related to the rise of a multidimensional ‘financial sector’ and to the greater competitiveness of other manufacturing countries. The result is an accelerating process of liberalization of the economy favored by the ascending financial sectors. Liberalization in pursuit of unregulated flows of investments, buyouts, acquisitions and trade increases the financial sector’s profits, commissions, incomes and bonuses. Liberalization facilitates the financial sector’s acquisition of assets. The declining competitiveness of the older ruling class manufacturing sector dependent on statist protectionism and subsidies leads to ‘rear-guard’ policies, attempting to fashion an unwieldy policy of liberalization abroad and protectionism at home.
The answer to the question of who rules depends on specifying the historical moment and place on the world economy. The answer is complicated by the fact that shifts among ‘sectors’ of the ruling class involves a prolonged ‘transitional period.’ During this period declining and ascending sectors may intermingle and the class members of declining sectors ‘convert’ to the rising sector. Hence, while power between economic sectors may change, the leading class groupings may not lose out or decline. They merely shift their investments and adapt to the new and more lucrative opportunities created by the ascending sector.
For example, while the US manufacturing sector has declined relative to ‘finance capital,’ many of the major investment institutions have shifted to the new financial ‘growth sectors.’ Concomitantly, the converted sectors of the ruling class will shift their policies toward greater liberalization and deregulation, thus severely weakening the rear-guard demands of the uncompetitive manufacturing sector. Equally important within the declining economic sectors of the RC, drastic structural changes may ensue, to regain profitable returns and retain influence and power. Foremost of these changes is relocation of production overseas to low wage, low tax, non-union locations, the introduction of IT technology designed to reduce labor costs and increase productivity, and diversification of economic activity to incorporate lucrative financial ‘services’.
For example General Electric has moved from manufacturing toward financial services, relocated labor intensive activity off-shore and computerized operations. Through these moves the distinction between ‘manufacturing’ and financial capital has been made obsolete in describing the ‘ruling class’.
To the degree that older manufacturing capitalists retain any economic and political weight in the RC, they have done so via sub-contracting overseas to Asia and Mexico (General Motors/Ford), invested in overseas plants to capture foreign markets, or have been converted in large part into commercial and importing operations (shoes, textiles, toys, electronics and computer chips).
Locally based manufacturers which remain in the RC are largely found among military contractors living off the largesse of state spending and depending on the political support of congressional and trade union officials, eager to secure employment for a shrinking manufacturing labor force.
During this transitional period of rapid and all-encompassing changes in the ruling class, enormous financial opportunities have opened up throughout the world. As a result of political tensions within the ‘governing class,’ key policymakers are drawn directly from the most representative institutions of Wall Street. Key economic policies, especially those which are most relevant to the RC, tend to be overwhelmingly in the hands of tried and experienced top leaders from Wall Street.
Despite (or because of) the ascendancy of various sectors of financial capital in the RC, and their agreements on a host of ‘liberalizing’ economic policies, they are not homogeneous in all of their political outlooks, party affiliations, or their foreign policy outlook. Most of these political differences are questions of small matter — except on one issue where there is a major and growing rift, namely in the Middle East. A sector of the RC strongly aligned with the state of Israel supports a bellicose policy toward the Jewish state’s adversaries (Iran, Syria, Hezbollah and Palestine) as opposed to another sector of the RC favoring a diplomatic approach, directed toward securing closer ties with Arab and Persian elites. Given the highly militarized turn in US foreign policy (largely due to the ascendancy of neo-conservative ideologues, the strong influence of the Zionist Lobby, and the instability and failures of their policies in the Middle East and China) the RC has pressed for and secured direct control over foreign economic policy.
The tensions and conflicts within the RC — especially between the Zioncons and the ‘free marketeers’ — have been papered over by the enormous economic benefits accruing to all sectors. All RC financial sectors have been enriched by White House and Congressional policies. All have benefited from the ascendancy of ‘liberalizing regimes’ throughout the world. They have reaped the gains of the expansionary phase of the international economy. While the entire ruling financial, real estate and trading sectors have been the main beneficiaries, it has been the financial groups, particularly the investment banks that have led the way and provide the political leadership.
Ascendancy of Financial Capital
‘Finance capital’ has many faces and cannot be understood without reference to specific sectors. Investment banks, pension funds, hedge funds, savings and loan banks, investment funds are only a few of the operative managers of a multi-trillion dollar economy. Moreover each of these sectors have specialized departments engaged in particular types of speculative-financial activity including commodity and currency, trading, consulting and managing acquisition and mergers. Despite a few exposes, court cases, fines and an occasional jailing, the financial sector writes its rules, controls its regulators and has secured license to speculate on everything, everywhere and all the time. They have created the framework or universe in which all other economic activities (manufacturing, retail sales and real estate) take place.
‘Finance capital’ is not an isolated sector and cannot be counterposed to the ‘productive economy’ except in the most marginal ‘local activity’. In large part finance capital interacts with and is the essential driving force in real estate speculation, agro-business, commodity production and manufacturing activity. To a large degree ‘market prices’ are as influenced by speculative intervention as they are by ‘supply and demand.’ Equally important, the entire architecture of the ‘paper empire’ (the entire complex of inter-related financial investments) is ultimately dependent on the production of goods and services. The structure of power and wealth takes the form of an inverted triangle in which a vast army of workers, peasants and salary employees produce value which becomes the basis for near and remote, simple and exotic, lucrative and speculative financial instruments. The transfer of value from the productive activities of labor up through the ladder and branches of financial instruments is carried out through various vehicles: direct financial ownership of enterprises, credit, debt leveraging, buyouts and mergers. The tendency of ‘productive capitalists’ is to start-up an enterprise, innovate, exploit labor, capture markets and then ‘sell-out’ or go ‘public’ (stock offerings). The financial sector acts as combined intermediary, manager, proxy-purchaser and consultant, capturing substantial fees and expanding their economic empires and preparing the way to higher levels of acquisitions and mergers. ‘Finance capital’ is the midwife of the concentration and centralization of wealth and capital as well as the direct owner of the means of production and distribution. From exacting a larger and larger ‘tribute’ or ‘rent’ (commission or fee) on each large-scale capital transaction, ‘finance capital’ has moved toward penetrating and controlling an enormous array of economic activities, transferring capital across national and sectoral boundaries, extracting profits and dumping shares according to the business, product and profit cycle.
Within the ruling class, the financial elite is the most parasitical component and exceeds the corporate bosses (CEOs) and most entrepreneurs in wealth and annual payments. It falls short of the annual income and assets of the super-rich entrepreneurs like William Gates and Michael Dell.
The financial ruling class is internally stratified into three sub-groups: at the top are big private equity bankers and hedge-fund managers, followed by the Wall Street chief executives, who in turn are above the next rung of senior associate or vice-presidents of a big private equity funds who is followed by their counterparts at Wall Street’s public equity funds. Top hedge fund managers and executive have made $1 billion dollars or more a year — several times what the CEO’s make at publicly traded investment houses. For example in 2006 Lloyd Blankfein, CEO of Goldman Sachs, was paid $53.4 million, while Dan Ochs, executive of the hedge fund Och-Ziff Capital paid himself $220 million dollars. That same year the Morgan Stanley CEO received $40 million dollars, while the chief executive of the hedge fund Citadel was paid over $300 million dollars.
While the ‘hedge fund’ speculators receive the highest annual salaries, the private equity executives can equal their hundreds of millions payments through deal fees and special dividend payments from portfolio companies. This was especially true in 2006 when buyouts reached a record $710 billion dollars. The big bucks for the private equity bosses comes from the accumulating stake executives have in portfolio companies. They typically skim 20% of profits, which are realized when a group sells or lists a portfolio company. At that time, the payday runs into the hundreds of millions of dollars.
The subset of the financial ruling class is the ‘junior bankers’ of private equity firms who take about $500,000 a year. At the bottom rung are the ‘junior bankers’ of publicly traded investment houses (‘Wall Street’) who average $350,000 a year. The financial ruling class is made up of these multi-billionaire elites from the hedge funds, private and public equity bankers and their associates in big prestigious corporate legal and accounting firms. They in turn are linked to the judicial and regulatory authorities, through political appointments and contributions, and by their central position in the national economy.
Within the financial ruling class, political leadership does not usually come from the richest hedge fund speculators, even less among the ‘junior bankers.’ Political leaders come from the public and private equity banks, namely Wall Street — especially Goldman Sachs, Blackstone, the Carlyle Group and others. They organize and fund both major parties and their electoral campaigns. They pressure, negotiate and draw up the most comprehensive and favorable legislation on global strategies (liberalization and deregulation) and sectoral policies (reductions in taxes, government pressure on countries like China to ‘open’ their financial services to foreign penetration and so on). They pressure the government to ‘bailout’ bankrupt and failed speculative firms and to balance the budget by lowering social expenditures instead of raising taxes on speculative ‘windfall’ profits.
The Dance of the Billions: Finance Capital Reaps the Profits from their Power
Speculators of the world had a spectacular year in 2006 as global equities hit double digit gains in the US, European and Asian markets. China, Brazil, Russia and India were centers of speculative profiteering as the China FTSE index rose 94%, Russia’s stock market rose 60%, Brazil’s Bovespa was up 32.9% and India’s Sensex climbed 46.7%. In large part the stock markets rose because of cheap credit (to speculate), strong liquidity (huge financial, petrol and commodity profits and rents) and so-called ‘reforms’ which gave foreign investors greater access to markets in China, India and Brazil. The biggest profits in stock market speculation occurred under putative ‘center-left’ regimes (Brazil and India) and ‘Communist’ China, which have realigned themselves with the most retrograde and ‘leading’ sectors of their financial ruling class.
Russia’s booming stock market reflects a different process involving the re-nationalization of gas and petroleum sectors, at the expense of the gangster-oligarchs of the Yeltsin era and the ‘give-away’ contracts to European/US oil and gas companies (Shell, Texaco). As a result huge windfall profits have been re-cycled internally among the new Putin era millionaires who have been engaged in conspicuous consumption, speculation and investment in joint ventures with foreign manufacturers in transport and energy related industries.
The shift toward foreign-controlled speculative capital emerging in China, India and Brazil as opposed to ‘national and state’ funded investment in Russia accounts for the irrational and vitriolic hostility exhibited by the western financial press to President Putin.
One of the major sources of profit-making is in the area of ‘mergers and acquisitions’ (M&A) — the buying and selling of multinational conglomerates, with $3,900 billion in deals for 2006. Investment banks took $18.8 billion dollars in ‘fees’ leading to multi-million dollar bonuses for ‘M&A’ bankers. M&A, hostile or benign, are largely speculative activity fueled by cheap debt and leading to the greater concentration of ownership and profits. Today it is said 2% of the households own 80% of the world’s assets. Within this small elite, a fraction embedded in financial capital owns and controls the bulk of the world’s assets and organizes and facilitates further concentration of conglomerates. The value of speculative M&A on a world scale is 16% higher than at the height of the ‘DOTCOM’ speculative boom in 2000. In the US alone, over $400 billion dollars worth of private equity deals were struck in 2005, three times higher than the previous year.
To understand who are the leading members of the financial ruling class one needs only to look at the ten leading private equity banks and the value and number of M&A deals in which they were engaged:
Private equity rankings by M&A deals (Year to Dec 20 2006)
US Value $bn Number
Blackstone 85.3 12
Texas Pacific 81.9 11
Bain Capital Partners 74.7 9
Thomas H Lee Partners 53.4 6
Goldman Sachs 51.2 5
Carlyle 50.0 14
Apollo Management l 44.9 7
Kohlberg Kravis Roberts 44.5 3
Merrill Lynch 35.9 3
Cerberus Capital Management 28.6 4
Industry Total 402.6 1,157
(Financial Times, 12/27/2006, p 13 — FT montage: Bob Haslett)
The crucial fact is that these private equity banks are involved in every sector of the economy, in every region of the world economy and increasingly speculate in the conglomerates which are acquired.
In the era of the ascendancy of speculative finance capital, it is not surprising that the three leading investment banks, Goldman Sachs, Lehman Brothers and Bear Stearns reported record annual profits, based on their expansion in Europe and Asia, and their transfer of profits from manufacturing and services to the financial sector. For the year 2006, Goldman Sachs (GS) recorded the most profitable year ever for a Wall Street investment bank, on the basis of big (speculative) ‘trading gains and lucrative investment in the world’s worst sweatshops in Asia. GS reported a 69% jump in annual earnings to $9.54 billion dollars. Lehman Brothers (LB) and Bear Stearns (BS) equity banks also recorded record earnings. LB earned a record $4billion for the year. SB earned a record $2.1 billion dollars. For the year Lehman set aside about $334,000 dollars per junior banker, while top speculators and bankers earned a big multiple of that amount.
For the year 2006 investment banking revenue reached nearly $38 billion dollars compared to $25 billion dollars in 2004 — an increase of 34% (Financial Times Dec. 13, 2006 p.15).
The dominance of finance capital has been nurtured by the speculative activity of the controllers and directors of state-owned companies. State ownership is an ambiguous term since it raises a further, more precise, question: ‘Who owns the state’? In the Middle East, there are seven state-owned oil and gas companies. In six of those companies, the principal beneficiaries are a small ruling elite. They recycle their revenues and profits through US and EU investment banks largely into bonds, real estate and other speculative financial instruments (FT Dec 15, 2006 p.11). State ownership and speculative capital, in the context of closed ‘Gulf-State’ type of ruling classes, are complementary, not contradictory, activities. The ruling regime in Dubai converts oil rents into building a regional financial center. Many Jewish-American-led Wall Street investment banks cohabitate with new Islamic-based investment houses, both reaping speculative returns.
Much of the investment funds now in the hands of US investment banks, hedge funds and other sectors of the financial ruling class originated in profits extracted from workers in the manufacturing and service sector. Two inter-related processes led to the growth and dominance of finance capital: the transfer of capital and profits from the ‘productive’ to the financial and speculative sector and the transfer of finance capital overseas, in the form of take-over of foreign assets now equivalent of around 80% of the US GDP. The roots of finance capital are embedded in three types of intensified exploitation: 1) of labor (via extended hours, transfer of pension and health costs from capital to labor, frozen minimum wage, stagnant and declining real wages and salaries); 2) of manufacturing profits (through higher rents, inter-sectoral transfers to financial instruments, interest payments and fees and commissions for mergers and acquisitions); and 3) via state fiscal policies by lowering capital gains taxes, increasing tax write-offs and tax incentives for overseas investments and imposing regressive local, state and federal taxes.
The result is increasing inequality between, on the one hand, senior and junior bankers, public, private equity, investment and hedge fund directors, and their entourage of lawyers, accountants and, on the other hand, wage and salaried workers. Income ratios range between 400 to 1 and 1,000 to 1, between the ruling class and median wage and salary workers is the norm.
Crisis of the Working and Middle Class: (Begin to Worry the Ruling Class)
Living standards for the working and middle class and the urban poor have declined substantially over the past thirty years (1978-2006) to a point where one can point to a burgeoning crises. While real hourly wages in constant 2005 dollars have stagnated, health, pension, energy and educational costs (increasingly borne by wage and salary workers) have skyrocketed. If extensions in work time and intensification of work place production (increases in productivity) are included in the equation, it is clear that living (including working) conditions have declined sharply. Even the financial press can write articles entitled: “Why Ordinary Americans have Missed Out on the Benefits of Growth” (FT November 2, 2006 p.11).
Financial and investment banks are in charge of advising and directing the ‘restructuring’ of enterprises for mergers and acquisitions by downsizing, outsourcing, give-backs and other cost-cutting measures. This has led to downward mobility for the wage and salaried workers who retain their jobs even as their tenure is more precarious. In other words, the greater the salaries, bonuses, profits and rents for the financial ruling class engaged in ‘restructuring’ for M&As, the greater the decline in living standards for the working and middle class.
One measure of the enormous influence of the financial ruling class in heightening the exploitation of labor is found in the enormous disparity between productivity and wages. Between 2000 and 2005, the US economy grew 12%, and productivity (measured by output per hour worked in the business sector) rose 17% while hourly wages rose only 3%. Real family income fell during the same period (FT November 2, 2006 p.11). According to a poll in the fall of November 2006, three quarters of Americans say they are either worse off or no better off than they were six years ago (FT November 3, 2006 p.13).
The impact of the policies of the financial ruling class on both the manufacturing and service sectors transcends their profit skimming, credit leverage on business operations and management practices. It embraces the entire architecture of the income, investment and class structure. The growth of vast inequalities between the yearly payments of the financial ruling class and the medium salary of workers has reached unprecedented levels. The financial elite receives something in the range of a ratio of 500 up to 1,000 times that of an average worker, depending on how narrowly or broadly we conceive of the financial ruling class.
Members of the financial ruling class have noted these vast and growing inequalities and express some concern over their possible social and political repercussions. According to the Financial Times (December 21, 2006), billionaire Stephen Schwartzman, CEO of the private equity group Blackstone warned “that the widening gap between Wall Street’s lavish pay packages and middle America’s stagnating wages risks causing a political and social backlash against the US’s ‘New Rich’.” Treasury Secretary and former CEO of Goldman Sachs, Hank Paulson admitted that median wage stagnation was a problem and that amidst “strong economic expansion many Americans simply are not feeling [sic!] the benefits” (FT November 2, 2006 p. 11).
Ben Bernanke, Chairman of the Federal Reserve Bank testified before the Senate that “inequality is potentially a concern for the US economy . . . to the extent that incomes and wealth are spreading apart. I think that is not a good trend” (Ibid). In 2005, the proportion of national income to GDP going to profits, rents and other non-wage and salary sources is at record levels: 43%. Inequality in the distribution of national income in the US is the worst in the entire developed capitalist world. Moreover studies of time series data reveal that in the US inequality increased far greater and intergenerational social mobility was far more difficult in the US than any country in Western Europe. The growth of monstrous and rigid class inequalities reflects the narrow social base of an economy dominated by finance capital, its ingrown intergenerational linkages and the exorbitant entry fees ($50,000 per annum tuition with room and board) to elite private universities and post-graduate business schools. Equally important, the political power of finance capital and its ‘associated’ conglomerates wield uncontested political power in the US in comparison to any country in Europe. As a result the US government redistributes far less through the tax and social security, health and educational system than other countries. (ibid)
While some financial rulers express some anxiety about a ‘backlash’ from the deepening class divide, not a single one publicly supports any tax or other redistributive measures. Instead they call for increases in educational up-grading, job retraining and greater geographical mobility, though it is precisely among the educated middle class which is suffering salary stagnation.
Neither the Democratic Party majority in Congress, nor the Republican-controlled Executive offer any proposals to challenge the financial ruling class’s dominance nor are there any proposals to reverse its most retrograde policies causing the growing inequalities, wage stagnation and the increasing rigidity of the class structure. The reason has been reported in the Wall Street Journal and the Financial Times: An overwhelming chunk of the funds that Democrats raise nationally for election campaigns comes either from Wall Street financiers or Silicon Valley software entrepreneurs. (FT November 3, 2006 p. 13). The Democratic congressional electoral campaign was tightly controlled by two of Wall Street’s favorite Democrats, Senator Charles ‘Israel First’ Schumer and Congressman Rahm Immanuel, who selectively funded candidates who were pro-war, pro-Wall Street and unconditionally pro-Israel. Democrats slated to head strategic Congressional committees like Zion-Lib Barney Frank have already announced they have ‘good working relations’ with Wall Street.
The Financial Ruling Class Also Governs
Ruling classes rule the economy, are at the top of the social structure and establish the parameters and rules within which the politicians operate. More often than not few actually engage directly in congressional politics, preferring to build economic empires while channeling money toward candidates prepared to do their bidding. Only when an apparent division occurs, especially within the Executive, between the interests of the ruling class and the policies of the regime will elite members of the ruling class intervene directly or take a senior executive position to ‘rectify’ policy.
Ruling Class Political Power: Paulson Takes Over Treasury
Several sharp divergences occurred during the Bush regime between finance capital and policymakers. These policies prejudiced or threatened to seriously damage important sectors of the financial ruling class. Theses include: 1) the aggressive militarist and protectionist policies pursued by senior Pentagon officials and ‘Zion-con’ Senators toward China; 2) the political veto by Congress of the sale of US port management to a Gulf State-owned company and of a US oil company to China; 3) the failure of the Bush regime to secure the privatization of social security and to weaken the regulatory measures introduced in the aftermath of the massive corporate (Enron and World Com) and Wall Street swindles, and 4) the need to put a check on the uncontrolled growth of fiscal deficits resulting from the Middle East wars, the ballooning trade deficits and the weakening dollar.
The headlines of the financial press (FT December 4, 2006 p.3) spell out finance capital’s direct intervention into key White House policy making:
“Goldman Sachs Top Alumni Wield Clout in White House” and “Former Bank Executives Hold Unprecedented Power within a US Administration.”
US financial and manufacturing ruling classes have long influenced, advised and formulated policy for US Presidents. But given the stakes, the risks and the opportunities facing the financial ruling class, it has moved directly into key government posts. What is especially unprecedented is the dominant presence of members from one investment bank — Goldman Sachs. In late November 2006, Goldman Sachs (GS) senior executive William Dudley took over the Federal Reserve Bank of New York markets group. Hank Paulson, ex-CEO of GS is Treasury Secretary — explicitly anointed by President Bush as undisputed czar of all economic policies. Reuben Jeffrey, a former GS managing partner is the chief regulator of commodity futures and options trading, Joshua Bolten, White House Chief of Staff (he decides who Bush sees, when and for how long — in other words arranges Bush’s agenda) served as GS executive director. Robert Steel, former GS vice chairman, advises Paulson on domestic finance. Randall Fort, ex-GS director of global security, advises Secretary of State Rice. The ex-GS officials also dominate Bush’s working group on financial markets and financial crisis management. The investment bankers wielding state power will control the Bush regime’s biggest housing giants (Fannie Mae and Freddie Mac), tax policy, energy markets — all issues that directly affect the investment banks. In other words, the financial banks will be ‘regulated’ by their own executives. The degree of finance capital’s stranglehold on political power is evidenced by the total lack of criticism by either party. As one financial newspaper noted: “Neither Mr. Bush nor Goldman have been criticized by Democrats for holding too many powerful jobs in part because the investment bank (GS) also has deep ties to Democrats. Goldman represented the biggest single donor base to the Democrats ahead of this (2006) year’s mid-term election.” (FT December 4, 2006)
Among Paulson’s first moves was to organize a top level delegation to China and a working group to work on forming a ‘strategic partnership’. Its task is to accelerate the ‘opening’ of China’s financial markets to penetration and majority takeovers by US operated investment funds. This represents a potential multi-trillion dollar window of opportunity. By seizing the initiative Paulson hopes to undercut the anti-China cohort of neo-con, Pentagon and White House militarists, as well as backwater backers of Taiwanese independence and Congressional chauvinist demagogues like Senator Schumer who threaten to undermine lucrative US-Chinese economic relations.
To lower the fiscal deficit, Paulson proposes to ‘reform’ entitlements — reduce spending on Medicare and Medicaid and to work out a deal with the Democrats to privatize Social Security piecemeal.
Where finance capital has not been able to fashion a coherent economic strategy is with regard to Washington’s Middle East wars. Because of the pull of the Zionist Lobby on many of leading lights of Wall Street — including its unofficial mouthpieces — the Wall Street Journal and the NY Times — Paulson has failed to formulate a strategy. He does not even pay lip service to the Baker Iraq Study Group report’s proposal to gradually draw down troops for fear of alienating some key senior executives of Goldman Sachs, Stern, Lehman Brothers et al who follow the ‘Israel First’ line. As a result, Paulson has to work around the Lobby by focusing on dealing with the Gulf city-state monarchies and Saudi Arabia in order to avoid another disastrous repetition of the Dubai Port management sale. Paulson above all wants to avoid Zionist political interference with the two way flow of finance capital between the petrol-financial-banking complexes in the Gulf States and Wall Street. He wants to facilitate US finance capital’s access to the large dollar surpluses in the region. It is not surprising that the Israeli regime has accommodated their wealthy and influential financial backers on Wall Street by drawing a distinction between ‘moderate’ (Gulf States) with whom they claim common interests and ‘Islamic extremists.’ Israeli Prime Minister Olmert has directed his zealots in the US-Jewish Lobby to take heed of the refinements in the Party Line in dealing with US-Arab relations.
Nevertheless with all its concentrated political power and its enormous wealth and economic leverage over the economy, Wall Street cannot control or avoid serious economic vulnerabilities or possible catastrophic military-political events.
The Future of the Financial Ruling Class
What is abundantly clear is that one of the main threats to world markets — and the health of the financial ruling class — is an Israeli military attack on Iran. This will extend warfare throughout Asia and the Islamic world, drive energy prices beyond levels heretofore known, cause a major recession and likely a crash in financial markets. But as in the case of the relationships between Israel and the US, the Zionist Lobby calls the shots and its Wall Street acolytes acquiesce. As matters now stand, the Jewish Lobby supports the escalation of the Iraq war and the savaging of Palestine, Somalia and Afghanistan. It has neutralized the biggest and most concerted effort by big name centrist political figures to alter White House policy. Baker, Carter, former military commanders of US forces in Iraq have been savaged by the Zionist ideologues. Under their influence the White House is putting into practice the war strategy presented by the ‘American’ Enterprise Institute (a Zioncon think tank). As a result parallel to Bush’s appointment of Paulson and Wall Streeters to run imperial economic policy, he has appointed an entire new pro-war civilian military-security apparatus to escalate and extend the Middle East wars to Africa (Somalia) and Latin America (Venezuela).
Sooner or later a break between Wall Street and the militarists will occur. The additional costs of an escalating wars, the continual ballooning debt payments, huge imbalances in the balance of payments and decreasing inflows of capital as multi-national repatriate profits and overseas central banks diversify their currency reserves will force the issue. The enormous and growing inequalities, the massive concentration of wealth and capital at a time of declining living standards and stagnant income for the vast majority, gives the financial ruling class little political capital or credibility if and when an economic and financial crisis breaks.
With foreign investors owning 47% of all marketable US Treasury bonds in 2006 compared to 33% in 2001 and foreign holdings of US corporate debt up to 30% today, from 23% just five years ago, a rapid sell-off would totally destabilize US financial markets and the economic system as well as the world economy. A rapid sell-off of dollars with catastrophic consequences cannot be ruled out if US-Zionist militarism continues to run amuck, creating conditions of extended and prolonged warfare.
The paradox is that some of the most wealthy and powerful beneficiaries of the ascendancy of finance capital are precisely the same class of people who are financing their own self-destruction. While cheap finance is fueling multi-billion dollar mergers, acquisitions, commissions and executive payoffs, heightened militarism operates on a budget plagued by tax reductions, exemptions and evasions for the financial ruling class and ever greater squeezing of the overburdened wage and salary classes. Something has to break the cohabitation between ruling class financiers and political militarists. They are running in opposite directions. One is investing capital abroad and the other spending borrowed funds at home. For the moment there are no signs of any serious clashes at the top, and in the middle and working classes there are no signs of any political break with the two Wall Street parties or any challenge to the militarist-Zionist stranglehold on Congress. Likely it will take a catastrophe, like a White House-backed Israeli nuclear attack on Iran to detonate the kind of crisis which will provoke a deep and widespread popular backlash of all things military, financial and made in Israel.
Featured Video
Anthrax War – CBC The Passionate Eye
or go to
Aletho News Archives – Video-Images
Book Review
Shattered Dreams: The HPV Vaccine Exposed (2019)
By Christina England – 30 Q&As – Book Review & Summary
Lies are Unbekoming | September 4, 2026
… Gardasil received FDA fast-track approval in 2006, Cervarix followed in 2009, and Gardasil 9 was approved in December 2014 with more than double the aluminium adjuvant content of the original. The commercial context is specific. Merck was about to lose patent protection on Zocor and faced $18 billion in Vioxx injury claims from a cardiovascular drug the company had marketed while suppressing its own data showing a five-times increase in heart attacks. Analysts projected the global HPV vaccine market at $4 billion by 2011, contingent on government-funded national programs for teenage girls. The 1986 National Childhood Vaccine Injury Act had already granted manufacturers complete liability immunity. By 2013, Japan had withdrawn its HPV vaccine recommendation after cataloguing severe adverse reactions in hundreds of girls. No Western government followed. The establishment position across the UK, US, Australia, and most of Europe held, and still holds, that the vaccines are safe and effective, that reported injuries are coincidental, and that cervical cancer prevention justifies the program. The book was published into this position, not against a vacuum.
Shattered Dreams sits alongside Mary Holland’s The HPV Vaccine On Trial and Viera Scheibner’s foundational vaccination work as part of the documented record on what has been done to a generation of teenage girls under the banner of cancer prevention. The full summary unpacks three specific findings: that Merck used the aluminium adjuvant itself as the “placebo” control in 92.5% of trial subjects, making it structurally impossible to detect excess reactions from the adjuvant; that Dr. Sin Hang Lee found HPV DNA fragments bound to aluminium in every one of sixteen Gardasil samples tested, and in the blood and spleen of a New Zealand girl six months after her third dose; and that in every country with high vaccination coverage, including Australia, the UK, Norway, and Sweden, cervical cancer rates have stopped declining and started rising specifically in the vaccinated cohort. Martínez-Lavín’s 2017 calculation puts the number needed to seriously harm with Gardasil 9 at 140, and the number needed to vaccinate to prevent one case at 1,757. Thirteen young women are seriously harmed for every one who benefits. The vaccine was approved on the basis of trials that could not detect what the trials were supposed to detect, and it is still being given to twelve-year-olds today. … Read full review
Blog Roll
 Aletho News
- Georgia’s Largest Healthcare System Will Fire Employees Who Refuse Flu Vaccine
- The Five-Year Fuel Crisis: Why the World Economy Is Paying for a War It Thinks Is Ending
- Trump’s Big Bluff on Iran
- Swiss scammed out of millions by Ukraine-linked call centers – media
- Germany facing potential ‘violent conflict’ with Russia – spy chief
- Ukraine’s EU neighbors reject new plea from Kiev – Politico
- British Transport Police Facial Recognition Trial Scanned 926,912 People With Zero Arrests
- House Bill Would Ban Federal Use of Flock ALPR Data
- Can a Spice Rival a Drug? 10 Head-to-Head Trials Put It to the Test.
- The oil routes around Hormuz face their own chokepoints
- If Americans Knew
- “We See Our Homes Now From A Satellite, Like Strangers”
- Watch “Gaza: Doctors Under Attack”, originally censored by BBC
- NAZA: Israeli embassies in UK and US promote rival documentary to challenge Gaza genocide allegations
- David Ellison appoints Israeli to lead merged Paramount-Warner studios
- Turkish Red Crescent helps elderly Gaza man walk again after Israel confiscates his prosthetic limb
- Four Palestinians Killed in Israeli Attacks in Gaza
- Two Palestinian youths killed and village razed as Israeli attacks on West Bank continue
- Two more Christian women victims of Israeli raids on Gaza
- Cruelty, Deprivation, Indignity: A Journalist’s 22 Months in Israeli Prison
- New IDF Website Frames Slain Gaza Journalists as Terrorists
- No Tricks Zone
- Latest European Green Energy Debacle; Portugal’s Largest Flagship Solar Park Insolvent!
- Green Energy Debacle: German Expert Professor Fritz Vahrenholt Warns Of Severe Economic And Social Consequences
- Two More Paleo Reconstructions Affirm Meters-Higher Sea Levels Across Ireland, Brazil 7000-6000 Years Ago
- New Study: Earth And Venus Surface Warmth Largely Explained By Convection And Lapse Rate, Not CO2 Or Radiation
- 2025 Nature Paper Claiming Worsening Global Drought Gets RETRACTED …Heavily Flawed
- New Study: ‘Global Drought Shows No Detectable Recent Acceleration Under Climate Warming’
- Economic Masterminds: German Socialists Suggest Taxing Productivity Gains Stemming From Using AI
- The South China Sea Has Not Been Cooperating With The Climate Change Narrative
- Energy Crisis: Germany Enters Heating Season With Historically Low Gas Reserve Fill Levels
- New Study: The Antarctic Ice Sheet Gained Mass From 2020-2024 Due To Staggering Snow And Ice Accumulation

