Russia readies end to Greek food embargo – Economy Minister
RT | April 8, 2015
Russia has drafted a number of proposals that could end the embargo on food products from Greece, Russia’s Economic Development Minister Aleksey Ulyukayev said at a meeting with Greek Prime Minister Alexis Tsipras on Wednesday.
“We’ll be discussing in detail this issue during the meeting of the Russian Prime Minister and his Greek counterpart tomorrow,” Ulyukayev told reporters, as quoted by TASS.
“We’ve prepared a number of proposals regarding the embargo issue for discussion,” the Economy Minister said.
Russia is also considering rescinding food sanctions against Cyprus and Hungary, according to Aleksey Pushkov, head of the Duma Foreign Affairs Committee.
Greece has been hit especially hard by the ban, as more than 40 percent of Greek exports are to Russia. In 2013, more than €178 million in fruits and conserves were exported to Russia, according to the Greek fruit export association, Incofruit-Hellas.
On March 3, Greece sent a letter to the Russian food watchdog Roselkhoznadzor requesting the temporary restrictions on agricultural products such as strawberries, kiwis, peaches, and seafood is lifted.
Up until the ban, Russia had been Greece’s biggest single trading partner worth $12.5 billion (€9.3 billion) by 2013, more than double the 2009 figure.
Russia’s agricultural food ban applies to EU countries and is not due to expire until August 2015, a year after the restrictions were imposed in response to Western sanctions.
Alexis Tsipras, the newly elected PM of Greece,is in Moscow for a two-day visit and meets Russian President Vladimir Putin on Wednesday afternoon. Distancing itself from its other EU members, Athens hopes to strike a chord of cooperation with Moscow.
“Your visit could not have come at a better time, as we must analyze what we could do together to restore the former rate of growth,” Putin said ahead of his meeting with Tsipras.
Tsipras has taken a hard-line stance against EU policies towards Russia,calling the sanctions a ”road to nowhere.”
Greece offers 5 key points for consensus with international creditors
RT | April 6, 2015
Greek Finance Minister Yanis Varoufakis has unveiled his plan on reviving the Greek economy by both meeting the IMF requirements and circuiting the austerity measures. A preliminary agreement over proposal is expected on April 24.
Greece expects to reach a preliminary agreement with creditor countries on financing the economy and the external debt at a meeting of eurozone finance ministers on April 24, Varoufakis said in an interview to Naftemporiki newspaper published Monday.
“Preliminary results will be achieved at the meeting of the Eurogroup on April 24,” he said adding that Greece expects to negotiate the unblocking of the last tranche of €7.2 billion from the EU loan program, and to negotiate restructuring of external debt of €324 billion, or 178 percent of GDP, by June.
The Greek authorities have also said they would pay a $450 million tranche of the IMF on April 9 and start a dialogue on economic issues, said the head of the IMF, Christine Lagarde Sunday after a meeting with Greek Finance Minister Yanis Varoufakis in Washington. Varoufakis, in turn, said the country intends to fulfill “all the obligations with respect to all the creditors.”
Both Lagarde and Varoufakis agreed that the uncertainty about Greece’s ability to repay debts is not in the interest of Athens. Earlier, there were fears that Greece wouldn’t be able to meet the next $450 million repayment of the IMF loan.
Greece and its international lenders have been at a dead end negotiating about Athens’ debt. The Troika of creditors insists that Greece sticks to the austerity measures in order to meet all its commitments.
Varoufakis says the austerity policy contravenes the election pledge of the newly elected government and demands the international creditors made concessions in restructuring the Greek debt.
In February, the Troika agreed to extend the bailout program until June.
Five points of Varoufakis’s plan
“Negotiations [with international lenders – Ed.] will be completed when we come to a decent agreement that will give a real prospect of stabilization and further substantial growth to the Greek economy,” said Varoufakis, noting that his Cabinet won’t agree to carry out measures leading to a recession.
Greece requires a new agreement with Europe to make its debt sustainable, said Varoufakis pointing out five terms on which the plan is expected to work out.
First, it is a reasonable level of primary budget surplus about 1.5 percent of GDP instead of 4.5 percent agreed by the previous government which has led to a severe recession.
Secondly, it is a reasonable debt restructuring that will link payments with the growth rate of nominal GDP.
In addition, Greece needs an investment package from the European Investment Bank and the European Investment Fund, which should be placed mainly in the private sector in accordance with the new, non-bureaucratic procedures.
Fourth, Greece should pass on effective restructuring of troubled loans by allocating them to a ‘Bad Bank’ unlike other resources of the Fund for financial stability.
The fifth thing is significant reforms that will give support to creative people and businesses that produce tradable goods, with export prospects, he added.
Read more: Greece preparing for Grexit, own currency – media
Where the Argentine Debt Case Stands Now, and Why it Still Matters
By Aldo Caliari – NACLA – 04/06/2015
In NML v Argentina, the world continues to witness a rare and surreal spectacle: the unpredictable consequences unleashed by a U.S. judge going rogue on the law. Last June, the U.S. Supreme Court validated a lower court ruling that granted investment group NML Capital the right to obtain payment of 100% of its claims against the Argentine government, setting a legal precedent whose impact is just beginning to become clear.
NML’s actions against Argentina demonstrate why the firm is frequently described as a “vulture fund.” After initially acquiring Argentine sovereign debt bonds following the country’s 2002 default, the investment group refused to accept the terms of the agreement that Argentina reached with over 92% of bondholders, in 2005 and 2010. Then, NML sued in U.S. courts for payment of 100% of its bonds’ value, plus interest, aiming to get what amounts to a 1600% return on its original investment.
NML’s lawsuit was part of a carefully thought-out script during Argentina’s long debt restructuring process, a strategy that vulture funds have exploited in the past. First, buy the debt of a country in trouble, on the cheap. Second, systematically reject any offer of a deal worth less than the whole claim. Third, wait until the country’s circumstances improve, aided by a mix of debt relief granted by other creditors and the normal healthy impacts that such debt cancellation, if timely and sufficient, will have on the debtor country’s economy. Then, sue for the whole amount of the claim plus interest.
It is easy to see that if all creditors followed this playbook—waiting for the debtor to get better without sacrificing any part of their credit—the strategy would not work.
Unfortunately, at the international level and for nations issuing sovereign debt, there is no recourse to anything like bankruptcy, so they are exposed to rulings – even divergent ones – made by judges with jurisdiction over particular bonds.
In this particular case, U.S. Judge Thomas Griesa decided to depart from the traditionally accepted interpretation of the pari passu clause typically inserted in sovereign bonds. Whereas the standard pari passu clause is normally understood to grant equality of rank and treatment, Griesa extended the interpretation to forbid Argentina from making payments on its restructured debt without also paying the holdout bondholders.
Argentina went ahead and deposited the payment for its restructured bondholders with the banks the instruments designate as fiduciaries – in charge of collecting the payment and giving it to the bondholders. Since the banks took the judge’s order to mean they could not disburse those funds, an anomaly has emerged: a country complying with its debt obligations falling into default due to a foreign court preventing payment from being disbursed. Amazingly, the unusual nature of the ruling was only the beginning of a sui generis scenario that continues to unfold.
Holders of bonds that were restructured under European or Argentinean jurisdiction filed claims arguing that by blocking payment on their credits—even when made by U.S. banks—Judge Griesa had overstepped his jurisdiction. In fact, the judge has already granted several “one-and-only-time” exceptions so the fiduciary banks could make payments to certain non-U.S. bondholders. When one of the banks, Citi, requested that the injunction be lifted for those payments, to avoid requesting an exception every time interest payments came due, the judge denied the request, only to later backtrack on his own decision. But while agreeing to give Citi this maneuvering room, the judge expanded the initial order – and the jurisdiction overstep – by ruling that future debt under Argentine law, if it will or can be paid in U.S. dollars, qualifies as external debt. So, financial entities helping Argentina make any such payments would be prevented from doing so by the court order.
An English court, in one of these cases, ruled that payments deposited with the fiduciary institution in New York are the property of the bondholders, and no longer belong to the debtor country. Therefore, they should not fall under the jurisdiction of a US judge. Indeed, therein lies another anomaly created by the judge’s ruling: His decision ignored the arrangement Argentina reached with 92% of creditors, but then issued measures that affect payments to these majority creditors—arguably bringing them coercively under his jurisdiction.
The Argentinean Congress also passed legislation according to which it will give non-restructured bondholders – such as NML – the same deal it granted to the restructured ones, but no more. To fulfill this commitment, the government has been depositing these payments in an Argentinean banking institution , which the “vulture funds” could claim at any moment if they so wished (so far they have not).
Some observers speculated that the Argentinean government would agree to settle with the vulture funds after expiration of the RUFO clause. RUFO stands for “right upon future offer” and is inserted in the restructured bonds to promise their holders they will have a right to be offered any better deal that other bondholders receive in the future. If Argentina had settled before the expiration of the clause, it could have faced immediate demands from majority bondholders for payments proportionally equal to those made to NML. But the expiration of the clause in January did not bring any change to Argentina’s offer to the vulture funds. These observers’ speculation failed to recognize that a settlement where NML gets paid the whole amount it demands—even in the absence of the “RUFO effects”—could invite lawsuits from other non-restructured bondholders. In fact, in the wake of the Supreme Court’s ruling last June, some of those bondholders have already filed suit hoping to follow in the footsteps of NML. Since these investors hold claims to some $15 billion, this is hardly an advisable course of action for Argentina.
Regardless of what happens with Argentina, however, repercussions from Griesa’s decision reach much farther. The ruling continues a trend that, legal experts say, has seen holdouts increasingly better treated by courts, at the expense of the soundness of sovereign debt restructurings. What former IMF economist Anne Krueger characterized in 2003 as a gap in the international financial architecture is now wider than ever. By increasing the potential rewards of holdout behavior, this recent judicial precedent will make future debt crises harder to resolve, with unpredictable systemic consequences.
At the same time, creditors might opt for a jurisdiction where the traditional understanding of pari passu still holds – such as England– at the expense of New York’s current dominance as a preferential jurisdiction for issuing sovereign debt. Indeed, a large number of prominent economists warned of this possibility following Griesa’s ruling.
Last September, facing the United States and other countries’ continuing resistance to reach a consensus, developing countries voted to create a sovereign debt workout mechanism, and negotiations have begun on establishing such a legal framework at the United Nations. Even in the worst-case scenario—failure to get all countries on board—these negotiations would create a U.N.-endorsed standard for settling future sovereign debt crises. If history is any guide, there is one thing we know for sure: sooner or later there will be a country that needs to resort to it.
Aldo Caliari has been, since 2000, staff at the Washington DC-based Center of Concern where, since 2002, he has been Director of the Rethinking Bretton Woods Project, focusing on linkages between trade and finance policy, global economic governance, debt, international financial architecture and human rights in international economic policy.
Greece preparing for Grexit, own currency – media
RT | April 3, 2015
Athens is currently trying to negotiate a new bailout deal with its Troika of creditors, but if that falls ‘Plan B’ could reportedly involve getting rid of the euro and cutting off its banking system from the European Central Bank.
Greece’s government is getting ready to nationalize the country’s banks and return to the the drachma, the Telegraph reported citing sources.
“We are a left-wing government. If we have to choose between a default to the IMF or a default to our own people, it is a no-brainer,” a senior official told The Daily Telegraph.
“We will shut down the banks and nationalise them, and then issue IOUs if we have to, and we all know what this means. What we will not do is become a protectorate of the EU,” according to another source.
The drachma was Greece’s currency from 1832 until 2002, when it switched to the euro. At the time, 1 euro equaled about 340 drachma.
When the financial crisis hit Iceland in 2008, the government decided to let the banks fail and default on $85 billion, and the country’s three main banks were nationalized. The transition was painful- the stock market plummeted 90 percent, unemployment jumped to 10 percent, and inflation ballooned to 18 percent. Though the economy still struggles with an unstable currency, a slow and steady recovery has occurred. GDP is finally back at pre-crisis levels, unemployment has improved to 5 percent, and inflation is below 2.5 percent.
Crunch day April 9
The Greek government has €463.1 million of IMF loans to be repaid by April 9 and another €768 million falling due in May.
After Greece does this, and the EU approves the reform proposals by Finance Minister Yanis Varoufakis, the Troika of lenders- the IMF, the European Central Bank, and the European Commission, is expected to release the next €7.2 billion tranche to Athens.
According to senior official, Syriza and Prime Minister Alexis Tsipras have the power to decide not to make the upcoming payments.
“We may have to go into a silent arrears process with the IMF. This will cause a furor in the markets and means that the clock will start to tick much faster,” the source told The Telegraph.
On Friday the Finance Ministry denied rumors they wouldn’t pay the €460 million sum on April 9.
Countries in the past that have defaulted in their IMF loans include Sudan, Peru, Liberia, the Congo, Somalia, Zambia, Guyana, Yugoslavia, Vietnam, Zimbabwe, and Iraq.
With its massive €316 billion debt, a collapse of the Greek economy has the potential to shake the rest of Europe. The reason the EU came to Athens’ rescue with two bailouts totaling 240 billion euro was to protect the euro currency, which at the time was shared by 18 separate countries, Greece included.
In the case that lending is cut off, Greek banks will overnight become insolvent and Athens would have to start printing its own currency to replace the euro.
In February, deposits in Greek banks declined by around €7.6 billon to a 10-year low of €140.5 billion, as customers started pulling out their money over growing concerns the country may leave the eurozone.
Options on table
Alexis Tsipras came to power in January on the promise of no more austerity from the EU, but has had to compromise many of his big ideals in order to receive more funds.
The four month extension agreed in February will expire at the end of June. In anticipation, Greek and EU officials will hash out a more permanent solution, which could include a third bailout package, or if Greece has its way, debt forgiveness.
Greece needs to receive about €17 billion in order to meet its payments for the rest of 2015.
Another option Greece has is to turn its back on its European creditors and look eastward, either to China or Russia, for a loan with less strings attached. The Greek PM is scheduled to visit Moscow and meet with President Vladimir Putin on April 9.
Former Greek Prime Minister Antonis Samaras has returned to the political arena to try and build a coalition to make sure Greece stays in the eurozone.
Read more: Greece submits 26-page reform plan to get €7.2bn bailout
Free Trade, Corporate Plunder and the War on Working People
By COLIN TODHUNTER | CounterPunch | April 3, 2015
Prior to last year’s national elections in India, there were calls for a Thatcherite revolution to fast-track the country towards privatisation and neo-liberalism. Under successive Thatcher-led governments in the eighties, however, inequalities skyrocketed in Britain and economic growth was no better than in the seventies.
Traditional manufacturing was decimated and international finance became the bedrock of the ‘new’ economy. Jobs disappeared over the horizon to cheap labour economies, corporations bought up public utilities, the rich got richer and many of Britain’s towns and cities in its former industrial heartland became shadows of their former selves. Low paid, insecure, non-unionised labour is now the norm and unemployment and underemployment are rife. Destroying ordinary people’s livelihoods was done in the name of ‘the national interest’. Destroying industry was done in the name of ‘efficiency’.
In 2010, 28 percent of the UK workforce, some 10.6 million people, either did not have a job, or had stopped looking for one. And that figure was calculated before many public sector jobs were slashed under the lie of ‘austerity’.
Today, much of the mainstream political and media rhetoric revolves around the need to create jobs, facilitate ‘free’ trade, ensure growth and make ‘the nation’ competitive. The endless, tedious mantra says ordinary people have to be ‘flexible’, ‘tighten their belts, expect to do a ‘fair day’s work for a fair day’s pay’ and let the market decide. This creates jobs. This fuels ‘growth’. Unfortunately, it does neither. What we have is austerity. What we have is an on-going economic crisis, a huge national debt, rule by profligate bankers and corporate entities and mass surveillance to keep ordinary people in check.
So what might the future hold? Unfortunately, more of the same.
The Transatlantic Trade and Investment Partnership
The Transatlantic Trade and Investment Partnership being negotiated between the EU and US is intended to be the biggest trade deal in history. The EU and US together account for 40 percent of global economic output. The European Commission tries to sell the deal to the public by claiming that the agreement will increase GDP by one percent and will entail massive job creation.
However, these claims are not supported even by its own studies, which predict a growth rate of just 0.01 percent GDP over the next ten years and the potential loss of jobs in several sectors, including agriculture. Corporations are lobbying EU-US trade negotiators to use the deal to weaken food safety, labour, health and environmental standards and undermine digital rights. Negotiations are shrouded in secrecy and are being driven by corporate interests. And the outcome could entail the bypassing of any democratic processes in order to push through corporate-friendly policies. The proposed agreement represents little more than a corporate power grab.
It should come as little surprise that this is the case. Based on a recent report, the European Commission’s trade and investment policy reveals a bunch of unelected technocrats who care little about what ordinary people want and negotiate on behalf of big business. The Commission has eagerly pursued a corporate agenda and has pushed for policies in sync with the interests of big business. It is effectively a captive but willing servant of a corporate agenda. Big business has been able to translate its massive wealth into political influence to render the European Commission a “disgrace to the democratic traditions of Europe.”
This proposed trade agreement (and others like it being negotiated across the world) is based on a firm belief in ‘the market’ (a euphemism for subsidies for the rich, cronyism, rigged markets and cartels) and the intense dislike of state intervention and state provision of goods and services. The ‘free market’ doctrine that underpins this belief attempts to convince people that nations can prosper by having austerity imposed on them and by embracing neo-liberalism and ‘free’ trade. This is a smokescreen that the financial-corporate elites hide behind while continuing to enrich themselves and secure taxpayer handouts, whether in the form of bank bailouts or other huge amounts of corporate dole.
In much of the West, the actual reality of neo-liberalism and the market is stagnating or declining wages in real terms, high levels of personal debt and a permanent underclass, while the rich and their corporations to rake in record profits and salt away wealth in tax havens.
Corporate plunder in India
Thatcher was a handmaiden of the rich. Her role was to destroy ‘subversive’ or socialist tendencies within Britain and to shatter the post-1945 Keynesian consensus based on full employment, fairness and a robust welfare state. She tilted the balance of power in favour of elite interests by embarking on a pro-privatisation, anti-trade union/anti-welfare state policy agenda. Sections of the public regarded Thatcher as a strong leader who would get things done, where others before her had been too weak and dithered. In India, Narendra Modi has been portrayed in a similar light.
His government is attempting to move ahead with ‘reforms’ that others dragged their feet on. To date, India has experienced a brand of ‘neo-liberalism lite’. Yet what we have seen thus far has been state-backed violence and human rights abuses to ‘secure’ tribal areas for rich foreign and Indian corporations, increasing inequalities, more illicit money than ever pouring into Swiss bank accounts and massive corruption and cronyism.
Under Modi are we to witness an accelerated ‘restructuring’ of agriculture in favour of Western agribusiness? Will more farmers be forced from their land on behalf of commercial interests? Officialdom wants to depopulate rural areas by shifting over 600 million to cities. It begs the question: in an age of increasing automation, how will hundreds of millions of agriculture sector workers earn their livelihoods once they have left the land?
What type of already filthy and overburdened urban centres can play host to such a gigantic mass of humanity who were deemed ‘surplus to requirements’ in rural India and will possibly be (indeed, already are) deemed ‘surplus to requirements’ once in the cities?
Gandhi stated that the future of India lies in its villages. Rural society was regarded as India’s bedrock. But now that bedrock is being dug up. Global agritech companies have been granted license to influence key aspects of agriculture by controlling seeds and chemical inputs and by funding and thus distorting the biotech research agenda and aspects of overall development policy.
Part of that ‘development’ agenda is based on dismantling the Public Distribution System for food. Policy analyst Devinder Sharma notes that the government may eventually stop supporting farmers by doing away with the system of announcing the minimum support price for farmers and thereby reduce the subsidy outgo. He argues that farmers would be encouraged to grow cash crops for supermarkets and to ‘compete’ in a market based on trade policies that work in favour of big landowners and heavily subsidised Western agriculture.
By shifting towards a commercialised system that would also give the poor cash to buy food in the market place, rather than the almost half a million ‘ration shops’ that currently exist, the result will be what the WTO/ World Bank/IMF have been telling India to for a long time: to displace the farming population so that agribusiness can find a stronghold in India.
We need only look at what happened to the soy industry in India during the nineties, or last year’s report by GRAIN, to see how small farmers are forced from their land to benefit powerful global agritech. If it cannot be achieved by unfair trade policies and other duplicitous practices, it is achieved by repression and violence, as Helena Paul notes:
“Repression and displacement, often violent, of remaining rural populations, illness, falling local food production have all featured in this picture. Indigenous communities have been displaced and reduced to living on the capital’s rubbish dumps. This is a crime that we can rightly call genocide – the extinguishment of entire Peoples, their culture, their way of life and their environment.”
Although Helena Paul is referring to the situation in Paraguay, what she describes could well apply to India or elsewhere.
In addition, the secretive corporate-driven trade agreement being negotiated between the EU and India could fundamentally restructure Indian society in favour of Western corporate interests and adversely impact hundreds of millions and their livelihoods and traditional ways of living. And as with the proposed US-EU agreement, powerful transnational corporations would be able to by-pass national legislation that was implemented to safeguard the public’s rights. Governments could be sued by multinational companies for billions of dollars in private arbitration panels outside of national courts if laws, policies, court decisions or other actions are perceived to interfere with their investments.
A massive shift in global power and wealth from poor to rich
Current negotiations over ‘free’ trade agreements have little to do with free trade. They are more concerned with loosening regulatory barriers and bypassing any democratic processes to allow large corporations to destroy competition and siphon off wealth to the detriment of smaller, locally based firms and producers.
The planet’s super rich comprise a global elite. It is not a unified elite. But whether based in China, Russia or India, its members have to varying extents been incorporated into the Anglo-American system of trade and finance. For them, the ability to ‘do business’ is what matters, not national identity or the ability to empathise with someone toiling in a field who happened to be born on the same land mass. And in order ‘to do business’, government machinery has been corrupted and bent to serve their ends. In turn, organisations that were intended to be ‘by’ and ‘for’ ordinary working people have been successfully infiltrated and dealt with.
The increasing global takeover of agriculture by powerful agribusiness, the selling off of industrial developments built with public money and strategic assets and secretive corporate-driven trade agreements represent a massive corporate heist of wealth and power across the world. The world’s super rich regard ‘nations’ as population holding centres to be exploited whereby people are stripped of control of their livelihoods for personal gain. Whether it concerns rich oligarchs in the US or India’s billionaire business men, corporate profits and personal gain trump any notion of the ‘national interest’.
Still want a Thatcherite revolution?
Colin Todhunter is an extensively published independent writer and former social policy researcher based in the UK and India.
Europe and the BRICS countries forge an independent rating system
By Ian BLOHM | Oriental Review | April 2, 2015
Despite attempts to portray the work of the “big three” as globally oriented, the rating agencies maintain a close link to the US financial institutions. The 2008 economic crisis sent their reputations reeling. Now the global market for making ratings needs to be de-monopolized and equipped with new, transparent tools for working with risk.
Currently, Fitch, Standard & Poor’s, and Moody’s enjoy almost complete legal immunity for their evaluations and are guaranteed high profits, regardless of the consequences. According to the French edition of Le Monde, between 2000 and 2007, Moody’s earnings quadrupled, thanks to CMBS, ABS, CDO, and other securities that had become the main source of the company’s financial gains, with a profitability margin of 52%. Unfortunately, accurate data on S&P and Fitch are not published, although it would be interesting to look at the accounting records of these organizations that insist on full transparency for everyone but themselves.
In any event, the US taxpayer makes up for any discrepancy between the rating and the reality – suffice it to recall the 2008 scandal over the ratings of “toxic” assets within the US banking system just before the collapse of Lehman Brothers.
The way it works
Rating agencies act as a “filter” regulating the movement of investment capital from developed markets into developing ones. The mechanism is simple – any rating assigned by the “Big Three” that is used by the head of a major investment fund affects the default risk. Actual business practice is often ignored. For example, the retirement accounts of America’s senior citizens can be invested into crazy foreign financial schemes, as long as their ratings are properly pitched. The rating system is designed so that cash from banks and investment funds passes only into the “right” hands under favorable terms. This creates a type of political road map for investors, which has little to do with the real macroeconomic indicators.
But this does not stop the experts from the “Big Three.” “Imagine a large group of people arguing strenuously with each other,” David Levey, a former managing director of Moody’s, told Foreign Affairs. “It could sometimes get to that. These were very exciting meetings and often there were substantial disagreements. In every case, the ultimate decision was made by majority vote.” But were any of the people involved in these debates elected? And on what basis did they wield such influence?
In 2011, this question was answered by William Harrington, a former senior president at Moody’s (a voice in the wilderness, indeed). “This salient conflict of interest permeates all levels of employment, from entry-level analyst to the chairman and chief executive officer of Moody’s corporation,” Harrington said in a filing to the US financial regulator, the Securities and Exchange Commission (SEC).
The myth that the rating agencies are a “global” business.
With a single stroke of a pen, highly rated players are given a significant competitive advantage based on their proximity to the source of investment. To ensure political control over developing markets, the analyses of all three ratings agencies always include assessment criteria that affect the overall result. At Moody’s, for example, those criteria are called “institutional strength” or “susceptibility to event risk.”
At their own risk and peril, agency analysts evaluate the stability of the institutions of a sovereign player, on the basis of some kind of “global” paradigm of historical development. Not one of the agencies is entirely forthcoming about its methodology for assigning ratings. And this is hardly surprising – how else to explain high ratings to the press, given sovereign bankruptcies, in, for example, Iceland?
The idea of global development, as part of a neoliberal world order, arose only recently (in the late 1980s) and is, like many ideological concepts, a political tool. The agencies, however, use this idea in all their documents, all the while professing objectivity. To evaluate developing markets, regardless of the local conditions, the “universal” IMF criteria are used, such as the degree of privatization and liberalization of the national economy. The crises in Latin America offer clear evidence of what happens when a government is prompted by the “ratings racket” to sell off its liquid assets during a period of financial instability.
 For example, in February 2015, the rating agency Moody’s downgraded the credit rating of the Brazilian oil and gas company Petrobras from Baa2 to Ba2, and as a result the company plunged from “investment grade” to “speculative.” The influential Brazilian edition of Jornal do Brasil calls that decision “absurd and premeditated robbery” and asks – what is more significant, the three million barrels per day produced by Petrobras or the opinion of a group of anonymous Moody’s analysts who upheld Greece’s high rating until the bitter end.
The “good” and “bad” guys
It has long been noted that if a more or less sovereign government comes to power in a country that has been exhausted by the neoliberal economic programmes, the “Big Three’s” ratings begin to drop as if by magic. The most remarkable story in recent times has been seen in France. In 2012 the French market, one of the most highly developed in the EU, found itself on the rating agencies’ “bad guys” list, due to its “incorrect” tax policy and the government’s refusal to relegate its local culture to the mercies of the anonymous forces of the financial market.
According to the journalist Édouard Tétreau, (Le Monde) in his article “The United States of Europe vs. the dream of Standard & Poor’s,” ratings are manipulated in order to “Balkanize” Europe. To counter this, he prescribes the creation of real banks in Europe that can “send the brokers on Wall Street and the City of London packing.” During the assaults on the EU’s credit, Antonio Tajani, a former vice president of the European Commission, told El País that the rating agencies “work for the dollar.” In short, when it comes to evaluating the real economic indicators, old Europe is doing its best to distance itself from the ratings.
Among Europe’s “good guys,” the rating agencies list only the minuscule economies of the Baltic states of Lithuania, Latvia, and Estonia, which in 2014 received upgraded investment ratings from S&P for their progress in tax reform.
In the US, the “Big Three” are evidence of the miracles of lobbying. On January 12, 2003, the state of Georgia passed strong anti-fraud laws drafted by consumer advocates. Four days later, Standard & Poor’s announced that if Georgia passed anti-fraud penalties for corrupt mortgage brokers and lenders, packaging including such debts could not be given AAA ratings. S&P’s move meant Georgia lenders would have no access to the securitization money machine. It is interesting that this situation arose five years before the time bomb known as the subprime crisis went off.
Is there an alternative?
The rating market is in dire need of de-monopolization. “We can’t have private companies, whose primary goal is maximizing profit, behaving like sovereign judges passing down opinions that are binding for disinterested third parties,” believes Thomas Straubhaar, the director of the Hamburg Institute of International Economics. The BRICS countries are solidly united with Europe in the search for alternatives to the “Big Three.”
New, transnational rating agencies, such as the Universal Credit Rating Group (UCRG), will be an important milestone in the rating market. UCRG was created in 2012 as a partnership between the Chinese rating agency Dagong, Russia’s RusRating, and United States’ Egan-Jones. The fundamental principle behind the formation of new transnational actors must be the requirement that they are unbiased and unaffiliated with any state or corporate entity.
Ian Blohm is the economist and international financial adviser of the Polish origin. He is currently based in Moscow and can be reached at ian_blohm@myway.com
Greece submits 26-page reform plan to get €7.2bn bailout
RT | April 2, 2015
The Greek Finance Ministry has put together a 26-page list of policy reforms, which calls for €19 billion in funds this year. The reforms also plan to tackle tax evasion, and propose a €1.5 billion privatization plan.
Greece’s international creditors- the European Commission, International Monetary Fund, and European Central Bank- must OK the detailed reform plan before Greece can unlock its next €7.2 billion in bailout funds and avoid going bankrupt. The Greek government is still hesitant to push through the reforms, as they don’t align with hardline promises made back in January.
Greek Finance Minister Yanis Varoufakis intended to submit the plan to parliament, but it was leaked and released early.
The Financial Times obtained and uploaded the document in its entirety.
The plan reaffirms that Greece has no plan to exit the euro currency or the European Union.
“The Hellenic Republic considers itself to be a proud and indefeasible member of the European Union and an irrevocable member of the eurozone,” the document said.
Greece believes it is “urgent” to close the chapter on twin bailout packages from the EU totaling over €240 billion, and to start a fresh deal with less strings attached. The IMF, European Central Bank, and European Commission only lent money to Greece under the condition of severe austerity measures. These budget tightening measures have stifled growth in Greece, which has been in recession for the last six years, and has created a rift between the Syriza party and the country’s creditors. Several reports have sparked it may be looking elsewhere for support, perhaps to Russia.
The Finance Ministry predicts 1.4 percent growth in the real economy in 2015, and unemployment to drop to 22.5 percent on the assumption there are no policy changes.
Tying up the loose ends that allow individuals and businesses to evade taxes remains a priority for the new Syriza government, as does privatization of state assets, which the current government believes has “failed spectacularly” in the past. In 2015, Greece hopes to raise a total of €1.5 billion in privatization revenues, after coming nowhere close to raising the previously proposed €50 billion between 2011 and 2016, of which only €2.6 billion was realized between 2011-2013.
The new, revised plan of the Syriza government is to raise €22.3 billion in revenues by 2020.
Other parts of the plan propose more luxury taxes and a gradual hike in the minimum wage.
The list is still a “very long way from being a basis (for a deal),” a eurozone official said, as quoted by Reuters.
Neither side has signaled that they are close to a new deal. Ministers from the EU and Greece hope to reach a breakthrough in negotiations at their next meeting on April 24.
The European Central Bank has been used as leverage against Greece, by only raising the emergency liquidity for Greek banks by miniscule amounts. The total emergency liquidity assistance now stands at €71.8 billion, which Greece believes is too small.
Greece has told its creditors that it will run out of cash by April 9, and may not be able to pay its €450 million repayment to the International Monetary Fund (IMF) if it didn’t receive a cash injection.
With its massive €316 billion debt, a collapse of the Greek economy has the potential to shake the rest of Europe.
The enduring reality of government by wealth and some of its consequences
By John Chuckman | Aletho News | April 2, 2015
If you really want to understand the world in which we live – its endless wars, coups, interventions, and brutality towards great masses of people – you need to start with a correct understanding of the political machinery at work. Talk of liberal interventions or fighting for rights, Western values, and democracy are hopelessly naïve and mostly deliberately deceptive. America’s record in such matters is one of securing everything from bananas, copper, and crude oil concessions to, at the very least, foreign governments obedient to its mandates after removing a disliked leader, whether elected or not. There is no concern for principles outside of their being featured in blowhard, insincere political speeches. The interests of America’s government do not match the interests of ordinary people, those in America or anywhere else, and, were the informed consent of the governed genuinely involved in launching bloody adventures, they likely never would happen.
The underlying reality of how people in the West are governed now compared to hundreds of years ago is surprisingly unchanged, much the way the rules governing how chemical bonds form have not changed despite a long and great parade of events and discoveries in the visible world. Despite all the revolts, revolutions, congresses, constitutions, and great movements over the centuries, we are in fact governed in the same essential way people were.
Of course to see this, you have to strip away the forms and rituals we have constructed over the centuries, forms and rituals which create impressive effects much like the green smoke and thunderous voice of the Wizard of Oz, a wizened old man who worked from his curtained control room, pulling levers and hitting buttons to create intimidating effects. Most Americans remain impressed with the smoke and thunder and cheap magic tricks, it requiring some dedicated effort to shake off well-done illusions, and, as I’ve written before, Americans work extremely hard in their jobs or live a kind of marginal life trying to scrape by on low wages or part-time work, either of which situations leaves little time or inclination to question what government is really doing and for whose benefit.
And so long as America remains under the rule of wealth, it is unlikely other states, as in Western Europe, will emerge from it because America’s establishment has such decisive influence – economic, financial, military, and political – over many of them.
What is considered as wealth changes over time and with economic development, and with those changes so do its interests as well as the practices of its power. Great deposits of copper ore or crude oil In the Middle Ages were virtually worthless. Wealth then was land for agriculture, forestry, and hunting, with the family names of owners determined by their estates. The revenue from that natural wealth was converted to great houses and jewels and the implements of war. War, too, was a source of wealth with most wars being little more than adventures for dominance and looting on a grand scale. Again, as in our own day, they were dressed up with slogans about principles or causes which had almost no meaning. The case of the “Christian” Crusades, which continued their pillaging and orgy of killing, on and off, for centuries, springs to mind. Soldiers and sailors, up until modern times, were not motivated by their paltry pay and poor supplies, it being understood as a condition of employment that they would enjoy a share of the bounty looted in any campaign.
Today, the forms of wealth are as diverse and complex as is our society, and many of them are not apparent to ordinary people in the way great estates and hunting rights and obligations in war and peace to great lords were apparent in 800. Even as late as, say, 1850, wealth in the form of belching factories employing armies of people was often still quite apparent, but today’s complex banking and securities and financial institutions are not well understood by most people, although they represent immense wealth just as real in its demands and power as estates and obligations of the 9th century. Wealth today also comes from huge global manufacturing concerns of every description often with operations scattered out of sight, great shipping and transportation fleets, or electronic and communications empires. Land itself remains an important form of wealth where it can produce industrial-scale crops or contains deposits of valuable minerals or can generate flows of electricity or has been developed into great cities or resorts. War remains a source of wealth, only on a scale which could not have been imagined a few hundred years ago, but the spoils no longer go to soldiers in professional armies, they go to those responsible for the war, often in forms not easily recognized, as with special rights and concessions and secret arrangements.
As the nature of wealth evolved from the Middle Ages to the Modern Era, outward forms and rituals of government also changed. We have moved from the near-absolute power of kings and autocrats through aristocracies and republics with senates to a great variety of forms, parliaments and congresses, which appear designed to yield, to one degree or another, the consent of the governed.
But appearances, as in the case of the Wizard of Oz, can be deceiving.
Today, a single wealthy individual cannot make the kind of demands upon ordinary people that marked arrangements in the Middle Ages – although that must be qualified as I’m sure anyone who has become involved in a dispute with a wealthy neighbor or a great corporation will be happy to explain – but the class of wealthy people can indeed make just such demands, and they do so all the time. You will be taxed to pay for the schemes that their lobbying establishes, your water and air will contain the pollution of their manufacturing and mining, your children will be sent to kill and die in their wars, the ethics or morals you were taught as a child will be trampled upon, and virtually all important legislation will deal with the rights and interests of wealth, and not those of the broad mass of people.
In America, once in four years you will be asked to choose between two names, both of which have been closely vetted by the powers that be, to elect as head of government. Not only have they been vetted, but the immense costs of their campaigns in reaching you on television, at rallies, and with opinion polls to regularly fine tune their words will be paid almost exclusively by those whose real interests are at stake in every major election, the wealthy and their important serving institutions of government. The end effect is not really all that different than the old single-candidate Soviet elections at which the press trained Americans to sneer.
Many of America’s founding fathers had dark suspicions about the existence of wealth being secure in the presence of democratic government, and that is why they created forms – mostly adapted from Britain, a place no one regarded as a democracy then – to keep wealth safe. Over a couple of centuries, the original arrangements were modified, the country moving from a tiny one percent or so privileged voters – for perspective, that’s roughly the same as the percent of voters in China’s Communist Party deciding who rules the country – to something approaching universal suffrage, but always arrangements were made to safeguard wealth against the assumed predations of democracy.
In elections for the American Senate, the legislative body with real power, authority, and privilege, you again will be asked to choose between two well-vetted and well-connected candidates. Others may run, but they will be rendered helpless by the vetted candidates’ flood of money and resources, you will never hear their voices, and America’s press – itself an empire of wealth serving wealth – will waste no time on their views. In the case of the Senate, you will be asked once in six years to vote, with the elections staggered so that only one-third of that body faces election at any time – a perfectly-conceived formula for keeping the old bunch in charge despite issues which might have generated election discontent. In fact, you can never “throw the bums out” in America. Anyway, there really isn’t much risk for Senators running for re-election, with incumbents winning about 95% of the time. Senate seats are so secure they sometimes become family sinecures, handed down from father to son. After the election, unless you live in a small-population, insignificant state, you will never see or meet your Senator, and you will certainly have no opportunity to lobby. Virtually all seeing, meeting, and lobbying will be done by the wealthy sponsors of the successful candidates or by their hired help.
The average American Senator is said to spend two-thirds of his or her time securing funds for the next election, and such elections have now been bid-up to unbelievable amounts of money. The huge costs serve as what economists call “a barrier to entry,” a kind of high financial wall which keeps others from entering the political market, or, if somehow they do manage to enter, keeps them from effectively competing. Only the other wealth-vetted and connected candidate will have any hope of collecting a big enough pot of money to threaten an incumbent. The belief that people giving millions of dollars to candidates expect nothing in return is not even worth discussing. What they get – apart from goodies like important and prestigious appointments or valuable government contracts – is access, and access is exactly what most people never enjoy. Intimate access to politicians in high office, people always mindful of the necessity for another overflowing campaign war chest, is genuine power.
It is not impossible to have compatibility between democracy and wealth, but it requires a set of laws and regulations concerned with campaign financing, lobbying, and dis-establishing a political duopoly of two privileged parties, laws which simply cannot happen in America over our lifetimes. In America, law makes corporations persons, and the highest court, packed by judges appointed to serve wealth’s interests, has ruled that campaign money is free speech. These are not things easily turned around.
The American system of campaign financing not only assures the secure power of domestic wealth, it assures also the influence of wealthy lobbies serving the interests of foreign states, Israel being the most outstanding example. Other foreign states also exploit this system to varying degrees, but no other state has more than five million American citizens in great part keen to serve its interests. And many of them are successful, affluent, and well-placed people enjoying a connected set of organizations and well-funded lobbies. Other foreign states also do not enjoy having many of their lobbyists in America being dual-citizens, free to move back and forth between the country being lobbied and the country being lobbied for, surely an ethical issue for politics and foreign affairs of the first magnitude. It is a unique situation in many respects, and it has helped create a unique set of problems in the world.
The wealthy interests of America happen to share some important interests with lobbyists for Israel, including securing [or limiting competition to] the Western world’s supply of energy and not permitting the rise of states of any power in the Middle East who disagree with America’s essential views. It is important to keep in mind that “America’s essential views” are not necessarily the views of most of the American people and that many of those “essential views” have never received genuine informed consent. Elections conducted the way America’s high-level elections are conducted are incapable of bestowing meaningful consent, especially in vitally important matters.
The Israeli-American alliance is something of an unholy one because in binding America so closely to Israel, some huge and unresolvable conflicts have been created. Israel is associated with a long series of wars and abuses in the region, and, ipso facto, so is America. Israel, given the nature of its founding, expansion, and practices, is not liked by any neighboring states, although many now cooperate secretly, and sometimes even openly, in areas of mutual interest and have learned to tolerate its existence, the way generally eased by large American bribes or equally large American threats.
Traditionally, states in the Middle East are not democracies. Their often short histories have given limited opportunity for wide-spread development and prosperity creating a strong middle-class, the sine qua non for democracy. With the United States always (insincerely) praising democracy – including Israel’s grotesque contradiction of “democracy for some but not others” – it has been caught in a bind between supporting what it says it opposes and opposing what it says it supports.
Its proposed solution was a huge CIA project, nick-named “the Arab Spring” by America’s wealth-serving and often dishonest press, a set of manufactured uprisings intended to bring a semblance of democracy to the region. It has been largely a failure, ending with some countries trapped in chaos or civil war and others, notably Egypt, briefly gaining a government Israel hated intensely, the truth being that genuine democracy in virtually any of these countries will not be friendly to Israel’s geopolitical ambitions in the region nor to those of its American promoter and protector. While the “Arab Spring” was allowed to proceed in some states, in others, where it was neither intended nor desired, such as Saudi Arabia or Bahrain, spill-over effects were deliberately and violently suppressed with American assistance. So the American-Israeli relationship now still locks the United States effectively in fighting against democracy in some countries and in supporting absolute monarchs and oligarchs in others, while in still others, such as Syria and Iraq, it is involved literally in smashing them as states, in violation of all international law and long-term good sense.
The entire situation is an ongoing disaster and is almost certainly not sustainable over the long term. How do you insist a huge country like Egypt remain a backwater without democratic rights indefinitely? How can you justify the destruction of an ancient and beautiful country like Syria? How can you justify supporting absolute monarchs and keeping their people in total political darkness? How do you continue supporting Israel in its abuse of millions, depriving them of every human right, or in its constant aggression to secure its hegemony? The drive for regional hegemony is all that is behind Israel’s constant hectoring of Iran, and how is that behavior different to the aggressive wars condemned by the Nuremburg Tribunal? It’s not, of course. Further, destructive, deliberately-induced conflicts like that in Syria, by degrading its economic advance, only slow the day for democracy’s having a real chance to emerge.
So here is America, self-proclaimed land of the free, mired in a vast situation where it works to suppress democracy, supports tyrants, and supports aggressive war because its leaders, with no genuine consent of the governed, have put it there, and this is just one of many unhealthy and destructive consequences of wealth’s rule in the United States. Wealth has no inherent interest in democracy, and it is entirely up to a people anywhere to demand respect for democracy through laws.
Soros Looks to Co-Own Ukraine
By Alex Freeman • TFC • March 30, 2015
Vienna, Austria – Billionaire hedge fund manager George Soros has proposed a $1 Billion contribution of a combined $50 Billion investment package in the Ukraine in order to form an economic barrier to Russia’s entry to the war torn nation. In an interview with an Austrian newspaper, Soros said, “The West can help Ukraine by increasing attractiveness for investors.” The Hungarian-born economic hitman may be more interested in helping his, and other investor’s, pockets, rather than the people of Ukraine. The speculation here could undermine any truly democratic action in Ukraine. By using low EU Central Bank interest rates to achieve his investments, Soros’s plans begin to bear marked similarities to speculations that destroyed the British Pound and took severe tolls in places like Argentina.
The business model is nothing new for Soros, who has engaged in similar investment projects in West Africa. He continues, “There are concrete investment ideas, for example in agriculture and infrastructure projects. I would put in $1 billion. This must generate a profit. My foundation would benefit from this … Private engagement needs strong political leadership.” In Nigeria, Cameroon, Uganda and others, Soros has leveraged his political connections to protect his business interests in those nations. Revenue Watch International, a Soros firm, assisted Uganda in the development of its fossil fuel drilling regulations. Open Society Institute, another Soros Non-Governmental Organization, has recently been responsible for setting up and later overthrowing presidents of Senegal and Congo. Soros maintains significant oil, gold and diamond drilling operations in these nations. The International Crisis Group, yet another Soros NGO, has repeatedly advised the US Government to provide American military intervention in these fragile societies heavy in natural resources.
The profits would certainly roll in for the relentless investor. Soros Fund Management, LLC maintains ownership of large share percentages in key corporations that will benefit from investment in Ukraine. Soros owns over 5 million shares of the chemical giant Dow Chemicals, with diversified products and services from industrial to agricultural applications. Another big agricultural winner would be Monsanto. Soros owns half a million shares of the bio-tech firm, which has been a part of most Ukraine political discussions since the civil conflict broke out two years ago. Ukraine has vast supplies of oil and natural gas. Energen, a natural gas utility, could be a prime developer of Ukraine’s fossil fuel reserves. Soros owns nearly two million shares of that company. PDC Energy, with one million shares owned, might be another contender for drilling profits. Soros also owns significant stakes of Citigroup, which stands to be a primary financial intermediary for any investment in Ukraine.
Soros’ investment strategy is not restricted to diversified holdings of major national and international corporations or mutual funds. A significant tactic is the investment in supportive elements within the US government. In 2014, Soros ranked 11th on OpenSecrets.org list of “Top Individual Contributors.” His nearly $4 Million open investment (contributions sourced directly to him and not channeled through 501c4 “dark money” organizations) could potentially amount to $400 Million dollars in returns, if not more. The Carmen Group, for instance, a lobbying company in Washington, has claimed that for every dollar invested in lobbying, their clients receive $100 in return. RepresentUs, a campaign finance reform advocacy group, has measured similar extensive gains for political contributions and lobbying expenditures.

United Republic Infographic for Return on Lobbying Investment
If Soros senses a $100 Billion profit, diversified through a number of companies he holds stakes in, he will not mind selling other countries, individual investors, or the IMF to provide the remainder of the $50 Billion total investment he thinks Ukraine needs. In fact, this was probably a major conversation topic this year at the Davos World Economic Forum meeting. The majority of these banks and corporations, however, will mine the profits from Ukraine, exporting them to other Western nations. Meanwhile, these corporations will burden Ukraine with significant loans, even if the rates are near zero. Even though these practices have devastated countries like Greece and Argentina, as long as the profits keep rolling in, the investments will continue.
Nationalizing Britain’s railways could cut fares 10% – campaigners
RT | March 31, 2015
Britons could see train fares slashed by up to 10 percent if the railway network was brought back under public ownership, a study by campaigners has revealed.
Passengers struggling to pay for season tickets could benefit from “massive” savings if profits creamed off by private operators and shareholders were reinvested back into a nationalized railway service.
Research by Action for Rail found that £1.5 billion could be saved over the next five years, as contracts held by 11 private firms operating the rail network come up for renewal.
With the potential savings, campaigners claim the government could introduce free off-peak travel for children traveling with their parents, season tickets could be cut by 10 percent by 2017 and by 2020 all ticket prices could be reduced by 3 percent.
Action for Rail estimated £520 million of savings could be made if shareholder dividends were given to the government.
The report comes as a poll of 1,000 voters found only 17 percent want railways to remain in the hands of private companies. The group We Own It, which compiled the results, said 40 percent of respondents wanted to see the whole network controlled by the state.
It follows separate research which revealed British travelers pay twice as much as a proportion of their salary on rail fares as passengers in Germany, France, Italy and Spain, where railways are publically owned.
The publication of the report also coincides with a day of action, with events held at more than 40 stations in the UK.
Frances O’Grady, TUC general secretary and chairman of Action for Rail, said: “The UK has the most expensive rail fares in all of Europe.
“If services were run by the public sector, it would make a big difference to families and hard-pressed commuters, who have suffered year after year of wage-busting fare increases under privatized rail.
“This report highlights once again the huge cost of privatization to taxpayers and passengers. Money that could be spent on making journeys cheaper is instead being siphoned off into shareholders’ pockets and wasted on bidding and other franchising costs.
“The case for an integrated rail network under public ownership is overwhelming.”
Transport will become a point of debate in the weeks leading up to the general election. The Labour Party is expected to broach the issue in its election manifesto, following comments from former Deputy PM John Prescott, who spoke in favor of ending privatization.
The only parties openly vying for re-nationalization are the Green Party and the Trade Unionist & Socialist Coalition.
A spokesman for the Rail Delivery Group, which represents Network Rail and train operators sounded a cautionary tone.
“The figures from Action for Rail should be taken with a large pinch of salt. Compared to the late 1990s, train companies are paying five times more money to government, largely because of phenomenal passenger growth on Britain’s railway, helping to fund big investment in better services.
“Increases to season tickets are regulated by government and operators offer a range of fares to suit the needs of different passengers, including some of the cheapest fares in Europe.”
Last summer’s Israeli aggression is sending Gaza back to the Middle Ages
Zionist colonisers destroy the tools for self-sufficiency of Palestinians in Gaza
By Miguel Hernández | International Solidarity Movement | March 31, 2015
Gaza, Occupied Palestine – Months after the last massive Israeli aggression against the Gaza Strip, thanks to the social and independent media, everyone has read news and seen pictures of the attacks from the Zionist regime against residential buildings, United Nations shelter-schools, hospitals, ambulances, mosques, churches and thousands of family homes.
However, little has been said about the almost complete destruction of Gaza’s industry and economy. As the Israeli Minister of Interior Eli Yishai said, the objective of the last operation was to “send Gaza back to the Middle Ages, destroying all of its infrastructure.” One of the more terrible blows committed towards this end has been the total destruction of the Beit Hanoun industrial area.
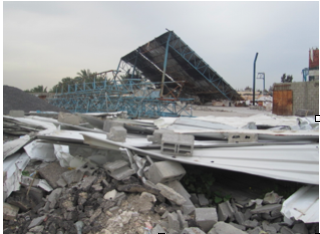 There were around 50 factories in Beit Hanoun, from which only three have been able to resume work seven months after the end of the assault.
 The factories in this industrial area provided work for 25% to 30% of Gaza’s population. Among the destroyed factories are those for paper, construction materials, clothing, medical equipment, plastic products, food and livestock products.
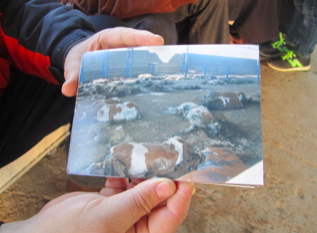 The agricultural industry has also been wounded by Israel’s summer attacks on Gaza. The owner of the Afanah Company showed us the pictures of his 800 cows killed by Israeli attacks during the last war on Gaza. Each cow was going to feed 7 families during the Eid holiday. Besides losing all his cows, Israel also destroyed the four fridges of the company, which contained 400 tons of meat.
Abu Fakhri Abu Ghais, from Beit Hanoun, explained how during the last massacre Israel killed his 17 sheep, and all his sons’ sheep, they destroyed all his farming equipment, worth over 15,000 US dollars. Israeli forces also destroyed the pumps for extracting the groundwater and the 20 tons of reserve of wheat seeds that Abu Fakhri had stored for the current year. The occupation also demolished the cabling that brought electricity to his village, Abu Safiya. He and his family now live in a tent without water or electricity, as his home was also destroyed.
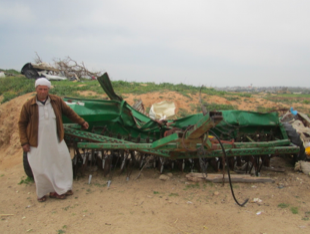 He and his family now live in a tent without water or electricity, as his home was also destroyed. Given the blockade imposed by Israel on the Gaza Strip, the struggling government of Hamas informed him that they don’t know when they’ll be able to restore the power supply, as they do not have available wire that is long enough.
In a Bedouin village located at the North of Beit Lahia, Hassan Sharadkha invited the author and his companions for a cup of tea in the wood cabin that he has built next to the rubble of his home. He showed us the pictures of everything he lost during the last summer at the hands of the Zionist occupation forces: 32 dunums of fruit and olive trees, 27 sheep and their stable, 2 cows, a 200 chicken farm, a horse, the water pump and the car he had just bought.
His older son, an electric engineer, was made unemployed because the solar panel company he worked for has also been bombed.
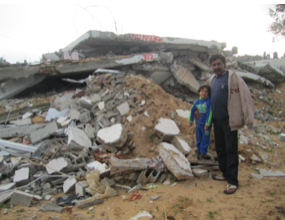 Ninety per cent of the Palestinian farmers in Gaza live in similar or worse circumstances.
 These attacks – against factories, farms, farming equipment and homes – were not by chance or accidental. These attacks demonstrate once again that the target of the genocidal Israeli colonialism is the Palestinian people itself, and that the war that Israel has been waging the last 66 years, under cover of Europe and the US, is against a nation, Palestine, that they seek to wipe off the map.
Why the West is to blame for the crisis in Ukraine: the full story
Chris Nineham reviews Frontline Ukraine: Crisis in the Borderlands by Professor Richard Sakwa
WE ALL KNOW about of the fog of war, but the current coverage and commentary on the crisis in Ukraine arguably takes wartime disinformation to new levels.
Richard Sakwa’s new book is a rare and precious exception. It is clear and measured and carefully researched and it shows that the story we are told in the west about events inside Ukraine is deeply flawed.
More generally, it exposes the idea that Russia is the aggressor and the West the protector of Ukraine’s democratic will as a travesty of the truth. In short, Sakwa’s analysis is diametrically opposed to what passes for an explanation of the Ukraine crisis in the mainstream.
One of the book’s great strengths is that it sees the crisis as a product of two connected processes, one domestic, one geopolitical.
Far from being a straightforward expression of popular will, Sakwa details how the government that emerged from the Maidan protests in February 2014 represented the victory of a minority hardline anti-Russian Ukrainian nationalism.
But this minority could come to dominate, he argues, because of the context provided by an aggressive, US-led, Western foreign policy designed to assert Western control over Eastern Europe and, at least in its more hawkish versions, de-stabilise Russia.
The push to the east
Nato and the EU have been pushing steadily eastwards ever since the end of the Cold War, despite verbal assurances from a series of Western leaders that this would not happen.
Twelve countries have joined Nato in the region since 1991. Georgia and Ukraine were promised membership at the Nato Summit in Bucharest in 2008, despite repeated warnings from the Russian government that taking Nato to the Russian border would cause a security crisis of the first order. It was only the intercession of Germany and France that forced the US to put these plans on hold.
The push to the east continued in the form, amongst others, of a plan to get Ukraine to sign up to an ‘Association Agreement’ with the EU. It was this agreement, due to be signed in November 2013, which sparked the crisis. To grasp its significance it is important to understand just how closely tied Nato and the EU have become, especially since the Lisbon Treaty signed by EU members in 2007.
Article 4 in the proposed Association Agreement committed the signatories to ‘gradual convergence on foreign and security matters with the aim of Ukraine’s ever deeper involvement in the European Security area’ (p.76). As Sakwa puts it, “it is pure hypocrisy to argue that the EU is little more than an extended trading bloc: after Lisbon, it was institutionally a core part of the Atlantic security community, and had thus become geopolitical”. (p.255)
All parties involved must have known that this document, if signed, would have caused existential anxiety in Moscow. Defenders of the West’s drive to the east justify it as the reflection of the will of the people concerned.
This is disingenuous. As Western leaders themselves have publicly admitted, a campaign to buy Ukrainain hearts and minds has been running for decades. In 2013, US Assistant Secretary of State for European and Eurasian affairs, Victoria Nuland, publicly boasted of the fact that the US had invested $5 billion in ‘democracy promotion’ since 1991, a huge sum by USAID’s standards (p.86). It has since been revealed that the EU too spent 496 million on front groups in Ukraine between 2004 and 2013 (p.90).
And there was nothing democratic about the process. Discussions about the Association Agreement in fact took place behind the backs of the Ukrainian people and the text of the agreement was not available in Ukraine till the last moment (p.74). It actually contained very little in the way of assistance to Ukraine’s economy, and its centrepiece was a radical liberalisation of EU-Ukraine trade, a direct threat to the traditional economic relations between Ukraine and Russia.
In the end, for a mixture of reasons, President Yanokovich didn’t sign up to the deal. But the pressure to sign helped to polarise the debate in Ukraine. The meaning of the agreement was an open secret in Washington. In the words of Carl Gershman from the National Endowment for Democracy, while Ukraine was ‘the biggest prize’, there was, beyond that, an opportunity to put Putin ‘on the losing end not just in the near abroad but within Russia itself’. (p.75)
Internal impact
This concerted Western strategy to surround and weaken Russia had a profound impact on the internal politics of Ukraine. Sakwa explains well the complex history that links Ukraine and Russia, a history that can’t be reduced to simple formulas of colonial dependency. The long, indigenous tradition of seeing Ukraine as part of greater Russian union has resulted in Russian being the dominant language in most of the country despite ethnic Russians being a relatively small minority. (p.8)
For all the mixed motivations behind the Maidan protests, it was a hardline anti-Russian strand that came to dominate, first in the protests themselves and subsequently in the regime that emerged out of the forced removal of the Yanukovich government.
Western policy in general gave ballast to a hardline nationalist tradition in the country that saw Russia – and the Russian minorities within the country – as the enemies of Ukrainian nationalism.
This tradition centred on the historic figure of Stepan Bandera who collaborated with the German Nazis in atrocities against Jews, Poles and Russians in Ukraine during WW2. His followers formed SS divisions which were responsible for the deaths of up to half a million people. (pp16-17). A giant poster of Bandera hung by the side of the stage in the Maidan, and many leaders of the regime that came out of the Maidan saw him as part of their tradition.
The West was minutely involved in this process. The State Department’s Victoria Nuland visited Ukraine three times in the first few weeks of the Maidan protests (p.86). The famous February leaked phone call between her and the US ambassador in Ukraine in which Nuland said ‘fuck the EU’, showed the extent to which the US was pulling the strings and in which direction.
In the call Nuland judges that the relatively moderate nationalist Vitaly Klitschko, who had the backing of Germany and the EU, should be kept out of office and that Arseniey Yatsenhuk – ‘Yats’ she calls him – a man who turned out to be a hardline chauvinist, should be the key player. Yatsenyuk indeed became the acting Prime Minister in the new government.
The result, in Sakwa’s words, was that, ‘what had begun as a movement in support of ‘European values’ now became a struggle to assert a monist representation of Ukrainian nationhood. The amorphous liberal rhetoric gave way to a much harsher agenda of integrated nationhood, and the euphoria promoted a rash of ill-considered policies’ (p.94).
As President Yanukovich was impeached and the new government was installed, armed insurgents strutted around the debating chamber. Yatsenyuk’s government was a mixture of recycled oligarchs and hard-line nationalists and fascists. It contained only two ministers from the entire south and east of the country, the areas with closest ties to Russia.
Five cabinet positions out of 21 were taken by the far right Svoboda Party, despite the fact they had only received 8% of the seats in Parliament. The minister of justice and the deputy Prime Minister came from the Russophobic Svobada party and its founder, a man with a long record of ultra nationalist activism, Andriy Parubiy, became head of the NSDC security agency.
Provocations
One of the new government’s first acts was to vote to rescind a law guaranteeing the right to instate a second official language where there were significant minorities. Although the change in the law was blocked, the vote was correctly interpreted as an attack on Russian minorities across the country.
It was followed by the outlawing of the Ukrainian Communist Party and the establishment of a ‘special service’ to root out fifth columnists in the armed forces (p.137). A wave of physical assaults on Russians duly followed.
In Odessa, pro-Russian activists were driven from an encampment into a trade union building which was then torched, killing a minimum of 48, many hundreds according to locals. The massacre was hailed by one of the Maidan leaders, Dmytro Yarosh, as ‘another bright day in our national history’ (p.98).
This series of events made a civil war virtually inevitable. Uprisings in the east of the country were motivated by political resentments, opposition to neoliberal policies and other economic grievances against Kiev, but most of all by a sense of the need for self defence. Unlike the largely middle-class movement in Kiev, the anti-Maidan movement in the Donbass region was ‘lower-class, anti-oligarchic (and Russian nationalist)’ (p.149). It was not mainly separatist. A poll by the Pew Research Center in May 2014 found that 70 per cent of eastern Ukrainians wanted to keep the country intact, including 58 per cent of Russian speakers (p.149).
The view from the East
Sakwa carefully analyses Russia’s behaviour during the crisis. His conclusions are a frontal challenge to the West’s narrative that the crisis in the Ukraine was precipitated by Russian aggression. As he shows, this is the opposite of the truth.
After the collapse of the Soviet Union, successive governments embraced a Western orientation, even making tentative moves to join Nato. In contrast to the stereotype that has been so carefully constructed, in his first term, Putin, and his successor Medvedev, sought engagement and accommodation with the West and tried to establish structured relationships with Nato and the EU. This approach faltered according to Sakwa, because of repeated rebuffs from the West:
“Continued conflicts in the post-Soviet space, the inability to establish genuine relations with the EU and disappointment following Russia’s positive demarche in its attempt to reboot relations with the US after 9/11 all combined to sour Putin’s new realist project” p.31
Over the last decade and a half, the Russian foreign policy establishment has become more and more alarmed by the unilateralism of US foreign policy, particularly over the invasion of Iraq and the attack on Libya. The non-negotiated push eastwards by Nato and the EU could of course only be perceived as hostile.
Even in these circumstances, however, for Sakwa, Putin’s central concern was to maintain the status quo in Ukraine, and try and ensure a friendly or at least neutral buffer state based on a stable settlement within the multi-ethnic Ukrainian state.
The forced, Western-backed removal of the Yanukovich government created an immediate crisis for the Russian government. Putin reacted by running a popular poll and an armed operation to secure the secession of the Crimean region to the USSR. Given the level of hostility and the mobilisations against Russian minorities, this can have surprised no-one. The Crimea was part of Russia until 1954, and it contains Sevastopol, Russia’s only major warm-water naval base. The idea that the Russian ruling class was going to stand aside and allow this area to be taken by a pro-Nato and anti-Russian government was obvious fantasy.
But if Putin’s long-term plan had been to invade, partition or even to destabilise the rest of Ukraine, he would have taken the opportunity presented by the virtual collapse of the Ukrainian government in February last year and the anti-Kiev uprisings in the east of the country which developed as a result.
His response was in fact was very different. Sakwa argues that despite the hoopla in the Western media, with the exception of the special case in Crimea, there is little evidence of significant military intervention by Russia in the months after the crisis of February, at least until August.
Putin supported the rebels to try and gain some leverage, but when it came to military assistance the rebels in the east were denouncing Putin for not delivering it. In Sakwa’s words, “Russia used proxies in the Donbas to achieve its goals within Ukraine, but this was not an attempted ‘land-grab’ or even a challenge to the international system” (p.182).
On 24 June in fact, the Russian Federation Council revoked a ruling which had previously allowed Russian military involvement in Ukraine ‘in order to normalise and regulate the situation in the eastern regions of Ukraine’ in the run up to tripartite talks involving the new Prime Minister Poroshenko (p.162). But Poroshenko had been the continuity candidate. On taking office, he had issued a statement calling for ‘a united, single Ukraine’ and characterising insurgents in the south-east as ‘terrorists’ (p.161).
Sakwa, along with most other sane commentators, is far from idealising the authoritarian and sometimes aggressive Russian regime. He criticises its human rights record and its institutions of governance. If anything his instincts are with a reformed integrationist ‘wider European project’, which, given the behaviour of the actually-existing Western institutions, seems a bit of a forlorn hope.
But what Sakwa’s book does so well is to ask us to go beyond rhetoric and generalities and examine the actual dynamics of the particular situation in its national and international dimensions.
Most importantly, he argues, we can’t begin to understand the Ukrainian catastrophe unless we completely reject the dominant, not to say consensual, Western account of what is happening. This is a crisis created by the West, but by threatening Russia’s core interests, it contains the possibility of a catastrophic confrontation; ‘the US has sought to create a regime in its own image, while Russia has sought to prevent the creation of one hostile to its perceived interests’ he argues (p.255).
We in the West have a responsibility to do everything possible to force our leaders back from the brink.
See also:
Richard Sakwa: History returns with a vengeance in Ukraine
Jonathan Steele: Who is really responsible for the crisis in Ukraine boiling over?
Featured Video

or go to
Aletho News Archives – Video-Images
From the Archives
The Forgotten Terrorist Pretext of the Vietnam War
By Jim Bovard | The Libertarian Institute | February 16, 2023
Since 9/11, terrorism has become the ultimate entitlement program for America’s political elite. Whether it is illegally spying on Americans or blowing Somali dissidents to pieces, invoking terrorism provides all the cover needed for Washington policymakers. But the disastrous results of granting politicians a blank check to fight terrorism should have been undeniable almost 60 years ago.
Back in the 1960s, terrorism was what the communists did. Anti-terrorist moral fervor and ideological blinders propelled the U.S. into its biggest foreign policy blunder since World War II. … continue
Blog Roll
 Aletho News
- LAPD Pilot Will Track Vehicles In San Fernando Valley
- Britain’s Online Censorship Law Now Comes With a Crisis Plan for Your Posts
- NATO’s “Nordic model” brings Arctic confrontation closer to Russia’s nuclear bases
- Using nuclear weapons, the US-Israeli alliance still can’t beat Iran
- Sunset on the Quality of Western Propaganda: Arrival of the Dr Strangelove Moment
- Ukrainian general accused of protecting crime bosses
- US-‘Israel’ alliance faces growing rupture after midterms
- GOP’s Crushing Midterm Loss Could Reshape US Political Landscape – Analyst
- Midterm loss gives Congress power to rein in US war on Iran
- Midterms Were ‘Vote of No Confidence’ in GOP, But Iran Has No Illusions About Democrats – Marandi
- If Americans Knew
- An error has occurred; the feed is probably down. Try again later.
- No Tricks Zone
- New Study: The Net Fossil Fuel Contribution To Rising Atmospheric CO2 Has Been Zero For 500 Years
- Germany’s Green Energy Transition Becoming Increasingly Expensive…Another 6 Trillion Euros!
- Sudden Stratospheric Warming, Powerful El Niño Combination May Lead To Extreme Europe Cold, Energy Crisis!
- Two New Studies Find Thwaites Glacier Melt Cannot Be Driven By Human Activity Or A Warming Ocean
- E-Cars Reduce CO2 Emissions By Only 41% Compared To Internal Combustion Engine Vehicles
- Predictions Made By Renowned Climate Professor Over Past Decades Have Been Proven To Be Poor
- New Study Suggests Large Regions Of The Pacific Ocean Have Been Cooling For The Last 80 Years
- Germany’s Green Energy Debacle: High Energy Costs Force Kahla Porzellan to Close After 182 Years!
- New Study: 50 Years Of The Most Aggressive ‘Net Zero’ Policies Can Only Affect The Global Climate By 0.03°C
- US September “Heat” Was No Record…Many Records Set Decades Ago

